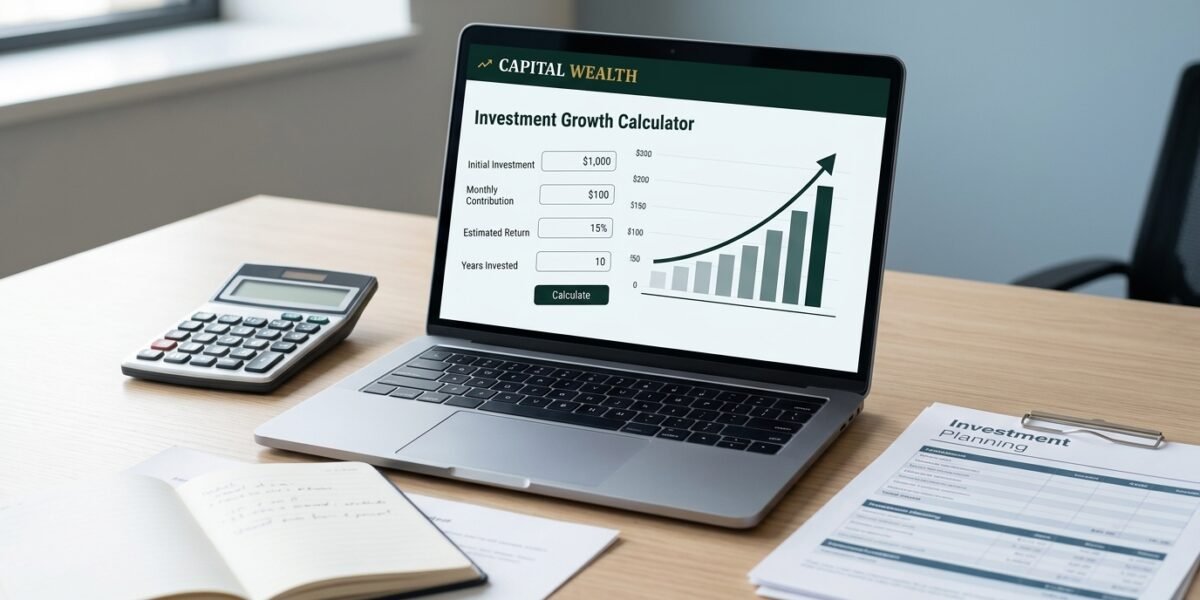
Investment Growth Calculator: How to Estimate Your Investment Growth
What Is an Investment Growth Calculator?
An investment growth calculator is a financial planning tool that helps you estimate how an investment could grow over time. It typically uses information such as your starting balance, expected rate of return, investment period, contribution amount, and contribution frequency to produce an estimated future value.
The main purpose of an investment growth calculator is not to predict exactly what your portfolio will be worth. Instead, it helps you understand how different assumptions can influence long term investment growth. You can use it to compare scenarios, understand the potential effect of compound growth, and see how regular contributions may affect a future balance.
For example, an investor may want to compare investing $200 per month for 20 years with investing $400 per month for the same period. An investment growth calculator can illustrate how the difference in contributions may affect the projected value.
The result is an estimate, not a promise. Actual investment performance can vary because markets fluctuate, investment fees reduce returns, taxes may apply, and the rate of return is rarely constant from year to year.
How Does an Investment Growth Calculator Work?
An investment growth calculator generally combines several financial inputs to estimate a future investment value. The exact inputs depend on the calculator, but the most common are initial investment, regular contributions, expected annual return, investment duration, and contribution frequency.
Initial Investment
The initial investment is the amount you already have available to invest. It could be $1,000, $5,000, $10,000, or another amount depending on your financial situation.
A larger starting amount can give compound growth more time to work on a greater base. However, you should not invest money that you may need for essential expenses or near term financial obligations simply to increase a calculator projection.
Regular Contributions
Regular contributions represent the money you add to your investment over time. Contributions can be monthly, quarterly, annually, or according to another schedule.
This input is particularly useful for people who invest part of their income regularly. Even when the starting investment is modest, consistent contributions over a long period can become an important part of the final balance.
Expected Rate of Return
The expected annual return is an assumption about how much the investment might grow on average each year. This is one of the most important inputs in an investment growth calculator because small changes in the assumed return can produce substantially different long term projections.
A projected return should not be treated as a guaranteed rate. Investments can produce positive or negative returns, and actual performance may differ significantly from a constant annual assumption.
Investment Period
The investment period is the amount of time the money remains invested. It may be measured in years or months.
Time can have a major effect on compound growth. An investment held for 30 years has more opportunity to compound than an otherwise identical investment held for 10 years.
Contribution Frequency
Contribution frequency determines how often additional money is invested. Monthly contributions are common in personal financial planning, but some calculators allow weekly, quarterly, or annual contributions.
The contribution schedule can affect the final estimate, particularly when contributions and compounding are modeled at different intervals.
Why Is an Investment Growth Calculator Useful?
An investment growth calculator can make an abstract financial goal easier to understand. Instead of simply thinking about saving for the future, you can model different scenarios and see how changes in time, contributions, or assumed returns could influence the result.
It can also help you identify which factors deserve the most attention. For some investors, increasing the regular contribution may be more realistic than assuming a higher return. For others, starting earlier may be the most important decision.
The calculator can therefore be useful for planning rather than prediction.
Understanding the Effect of Time
Time is one of the most important elements of long term investing. Compound growth means that returns can potentially generate additional returns over time.
Consider a simplified example. If an investment grows and the earnings remain invested, future growth may apply to both the original amount and previously accumulated earnings. The longer this process continues, the more noticeable the compounding effect can become.
An investment growth calculator helps visualize this process across different time periods.
Comparing Contribution Levels
You can use the calculator to compare different savings rates. For example, you could model a $100 monthly contribution and then compare it with a $250 or $500 monthly contribution.
The purpose is not to encourage an unrealistic savings target. Instead, the comparison can show how a manageable increase in regular contributions might influence a long term goal.
Testing Different Assumptions
Financial planning involves uncertainty. An investment growth calculator allows you to test several assumptions rather than relying on one projection.
You might create a conservative scenario, a moderate scenario, and a more optimistic scenario. The important point is to recognize that these scenarios are illustrations rather than forecasts of guaranteed performance.
How Compound Growth Affects Investments
Compound growth occurs when investment earnings remain invested and can contribute to future earnings. Over time, this can cause growth to build on an increasingly larger balance.
The effect can be difficult to appreciate when looking at only one year. A calculator makes the concept easier to visualize by showing how a balance may develop over a longer period.
Suppose an investor starts with $5,000 and earns a hypothetical average return while leaving the earnings invested. If the investment produces returns, future calculations can be based on a larger balance than the original $5,000.
The actual path will not necessarily resemble a smooth calculator projection. Markets can rise and fall, and real investment returns can vary considerably between years.
An investment growth calculator often simplifies this complexity by applying an assumed rate over the selected period. This makes the tool useful for illustrating compounding but also explains why its results should be interpreted carefully.
Investment Growth Calculator Example
Consider a hypothetical investor who starts with $5,000 and contributes $250 each month. Assume the investor uses a hypothetical annual return of 7% and keeps the money invested for 20 years.
An investment growth calculator can use these assumptions to estimate a potential future balance. The calculation may also show how much money came from the investor’s own contributions compared with the estimated investment growth.
The purpose of this example is educational. A 7% annual return is an assumption for the illustration and does not mean an investment will actually earn 7% every year.
Changing the assumptions can produce very different results. If the contribution increases, the estimated balance generally rises. If the investment period becomes longer, the opportunity for compounding increases. If the assumed return decreases, the projection can be substantially lower.
This is why comparing scenarios can be more useful than focusing on one calculator result.
What Factors Can Change Investment Growth?
Several factors can influence actual investment outcomes. An investment growth calculator usually simplifies these factors, so understanding the limitations is important.
Investment Returns
Investment returns can vary over time. A calculator may use a constant assumed annual return, but actual markets do not normally deliver the same result every year.
A portfolio might experience strong growth in one year, decline in another, and produce a smaller gain in a third year. The sequence of returns can matter, particularly when money is being withdrawn.
Investment Fees
Fees can reduce investment returns. Depending on the account and investment product, investors may encounter management fees, fund expenses, trading costs, advisory charges, or other expenses.
A calculator that does not include fees may show a higher projected value than an otherwise similar calculation that accounts for costs.
Before relying on an estimate, check whether the calculator allows fees to be included.
Taxes
Taxes can also affect the amount an investor ultimately keeps. The treatment of investment income and gains depends on factors such as the account type, investment, and applicable tax rules.
Because tax rules can change and differ between jurisdictions, an investment growth calculator should not be treated as a tax calculation unless it specifically provides that functionality.
Inflation
Inflation reduces purchasing power over time. A future balance may appear large in nominal terms while buying less than the same amount would buy today.
For long term financial planning, it can be useful to consider both a nominal future value and an inflation adjusted perspective.
Withdrawals
Many basic calculators assume that money remains invested throughout the selected period. Real investors may withdraw money for education, housing, retirement, emergencies, or other needs.
Withdrawals can reduce the amount available for future compounding and therefore change the eventual outcome.
Investment Growth Calculator and Regular Investing
Regular investing is a common approach in which an investor contributes a set amount at regular intervals. An investment growth calculator can help demonstrate the potential effect of maintaining that habit over many years.
For someone earning a regular income, monthly investing may be easier to plan than attempting to identify the perfect time to make a large investment.
For example, a person could model a fixed monthly contribution and then examine what happens if the contribution is increased after a salary increase. This turns the calculator into a planning tool rather than simply a future value estimator.
However, the calculator cannot determine whether a particular investment is suitable for an individual. Risk tolerance, financial goals, emergency savings, debt, time horizon, and other personal circumstances also matter.
How to Use an Investment Growth Calculator Step by Step
Using an investment growth calculator is usually straightforward.
Step 1: Enter Your Starting Amount
Enter the amount you currently plan to invest. If you are starting from zero, many calculators allow you to enter zero as the initial balance.
Step 2: Add Your Regular Contribution
Enter the amount you expect to invest regularly. Try to use an amount that is realistic for your budget rather than an amount that looks attractive in a projection.
Step 3: Select the Investment Period
Choose how long you expect the money to remain invested. Consider your actual financial goal when selecting the time period.
Step 4: Enter a Reasonable Return Assumption
Use a reasonable assumption and understand that it is not guaranteed. If you are uncertain, consider comparing multiple return assumptions rather than relying on one number.
Step 5: Review the Result
Look at the projected ending balance, total contributions, and estimated growth if the calculator provides those figures.
Step 6: Test Other Scenarios
Change one input at a time. You could compare a shorter and longer investment period, different contribution amounts, or different return assumptions.
This process can help you understand which variables have the greatest effect on the projection.
Investment Growth Calculator vs Simple Savings Calculator
An investment growth calculator and a savings calculator can appear similar, but they may be designed for different purposes.
A savings calculator may focus primarily on deposits and an interest rate, while an investment growth calculator may be designed to illustrate market based growth and recurring contributions.
The distinction matters because investment returns are uncertain. A savings account with a stated interest rate may have a different risk and return structure from an investment portfolio.
Before using a calculator, check what type of return it assumes and whether the tool is intended for investments, savings, or another financial product.
Investment Growth Calculator vs Compound Interest Calculator
A compound interest calculator generally focuses on the mathematical effect of interest being added to an account over time. An investment growth calculator may include additional elements such as recurring contributions and investment periods.
Both tools can demonstrate compounding, but their assumptions and intended uses may differ.
If you are comparing calculators, check whether they use the same compounding frequency, contribution timing, fees, taxes, and return assumptions. Two tools can produce different estimates even when their starting amount appears identical.
Common Mistakes When Using an Investment Growth Calculator
Assuming the Projection Is Guaranteed
One of the biggest mistakes is treating an estimate as a promise. Investment markets involve uncertainty, and actual results can be higher or lower than a calculator projection.
Choosing an Unrealistically High Return
A high assumed return can make the projected future value look attractive. However, the output is only as realistic as the assumptions used.
Ignoring Fees
Small recurring costs can affect long term growth. If your calculator does not account for fees, remember that the displayed result may not represent your actual net outcome.
Forgetting Inflation
A future dollar amount does not necessarily have the same purchasing power as money today. Long term projections should be considered in the context of inflation.
Using an Unaffordable Contribution
A calculator may show that increasing contributions can produce a larger projected balance. That does not mean you should contribute an amount that damages your current financial stability.
Focusing Only on the Final Number
The final projected balance is only one part of the calculation. Review the assumptions behind it, including time, contributions, return, fees, and compounding frequency.
How to Make Investment Calculator Results More Useful
The quality of an investment growth estimate depends heavily on the assumptions you enter.
Start with realistic contribution amounts. If your income changes over time, you can create multiple scenarios rather than assuming one contribution will remain unchanged forever.
Next, compare several return assumptions. This can demonstrate how sensitive the result is to market performance.
You can also compare different investment periods. A five year projection may look very different from a 20 or 30 year projection.
Finally, consider whether fees and inflation are included. If they are not, remember that the displayed future value may need additional interpretation.
Is an Investment Growth Calculator Accurate?
An investment growth calculator can be mathematically accurate based on the inputs and formula it uses, but that does not mean its prediction of your future investment value will be accurate.
This distinction is important. The calculation can correctly apply a formula to an assumed return while the assumed return itself may not match actual future performance.
For example, if a calculator assumes the same return every year, it creates a simplified model. Real markets may experience gains, losses, periods of limited growth, and significant volatility.
Therefore, an investment growth calculator is best viewed as a scenario planning tool.
Can an Investment Growth Calculator Help With Retirement Planning?
Yes, an investment growth calculator can be useful as one part of retirement planning. It can help illustrate how starting savings, regular contributions, time, and assumed returns interact.
However, retirement planning involves more than estimating an account balance. You may also need to consider expected expenses, inflation, taxes, retirement age, withdrawals, healthcare costs, other income sources, and changes in investment strategy.
A calculator can help you ask better planning questions, but it should not replace a complete financial plan.
How Much Should You Invest Each Month?
There is no universal monthly investment amount that is appropriate for everyone. The right amount depends on income, expenses, debt, emergency savings, financial goals, risk tolerance, and other circumstances.
Instead of selecting a contribution simply because an investment growth calculator produces an attractive result, start with an amount that fits your financial plan.
You can then test how gradually increasing that contribution could affect long term projections.
For example, someone might compare $100, $200, and $300 monthly contributions. The comparison can demonstrate the potential benefit of saving more without assuming that every investor can immediately afford the highest amount.
What Is More Important: Time or Investment Amount?
Both matter, and their relative impact depends on the circumstances.
Starting earlier gives an investment more time to potentially compound. Increasing contributions can also increase the amount of capital available for potential growth.
An investment growth calculator makes it possible to compare these factors. You might model an investor who starts with a smaller contribution at a younger age against another investor who begins later but contributes more.
The result should not be interpreted as a universal rule. Different investments, returns, fees, taxes, and personal circumstances can produce different outcomes.
The broader lesson is that time and consistent investing can be important considerations in long term financial planning.
Should You Change Your Investment Assumptions?
You should review your assumptions when your financial circumstances or goals change. A change in income, contribution level, investment strategy, time horizon, or financial objective may justify creating a new scenario.
You should also avoid constantly changing assumptions simply because markets have recently performed well or poorly. Short term market movements do not necessarily provide a reliable basis for predicting future returns.
Using an investment growth calculator periodically can help you review your plan without turning every market movement into a reason to change your long term strategy.
Benefits and Limitations of an Investment Growth Calculator
An investment growth calculator offers several useful benefits:
It makes compound growth easier to visualize.
It helps compare different contribution levels.
It can illustrate the effect of investing for different periods.
It can help users understand the relationship between contributions and potential growth.
It provides a simple way to create financial planning scenarios.
At the same time, it has limitations:
It cannot predict future market returns.
It may not account for every fee or tax.
It may simplify inflation.
It may assume a constant return.
It may not reflect withdrawals or changing contributions.
It cannot determine whether an investment is appropriate for a particular person.
Understanding both sides makes the calculator more useful and reduces the risk of interpreting a projection as a forecas
FAQs
What does an investment growth calculator show?
An investment growth calculator estimates how an investment could grow based on inputs such as starting balance, contributions, assumed return, and investment period. The result is a projection rather than a guaranteed outcome.
Can an investment growth calculator predict stock market returns?
No. It cannot reliably predict future market returns. It generally applies an assumed rate of return to create an illustrative scenario.
Does an investment growth calculator include compound growth?
Many investment growth calculators model compound growth, but the exact method varies. Check the calculator’s assumptions and compounding frequency before interpreting the result.
Does an investment growth calculator account for inflation?
Not always. Some calculators include an inflation adjustment while others show only nominal future values. Check the calculator settings before using the result for long term planning.
Should investment fees be included in an investment growth calculator?
If the calculator provides a fee input, including realistic fees can make the estimate more useful. Fees can reduce the amount of money that remains invested and compounds over time.
Can I use an investment growth calculator for retirement planning?
Yes. It can help illustrate potential accumulation, but retirement planning also involves expenses, taxes, withdrawals, inflation, other income, and investment risk.
Final Takeaway
An investment growth calculator can be a useful tool for understanding how starting capital, regular contributions, time, and assumed investment returns may interact. Its greatest value is helping investors explore scenarios and make long term planning concepts easier to understand.
The most important point is that calculator results are estimates, not guarantees. Real investment performance can fluctuate, fees and taxes can reduce results, and inflation can affect purchasing power.
Use an investment growth calculator to test realistic scenarios, compare different approaches, and understand the potential effect of long term investing. Then evaluate the results alongside your broader financial situation and verify current investment terms with appropriate official or professional sources when necessary.
You may also find blog on below
Exeter Finance Payment Options and Grace Period
Related Wealth Articles
Interest Calculator Credit Card: How to Calculate Interest and Payments
An Interest calculator credit card helps you estimate how much interest you may pay on a credit card…
Whole Life Insurance: How It Works, Benefits, Costs and Risks
Whole life insurance is a type of permanent life insurance designed to provide coverage for the insured person’s…