Lucid Group Options Trading Strategy: What Traders Need to Know
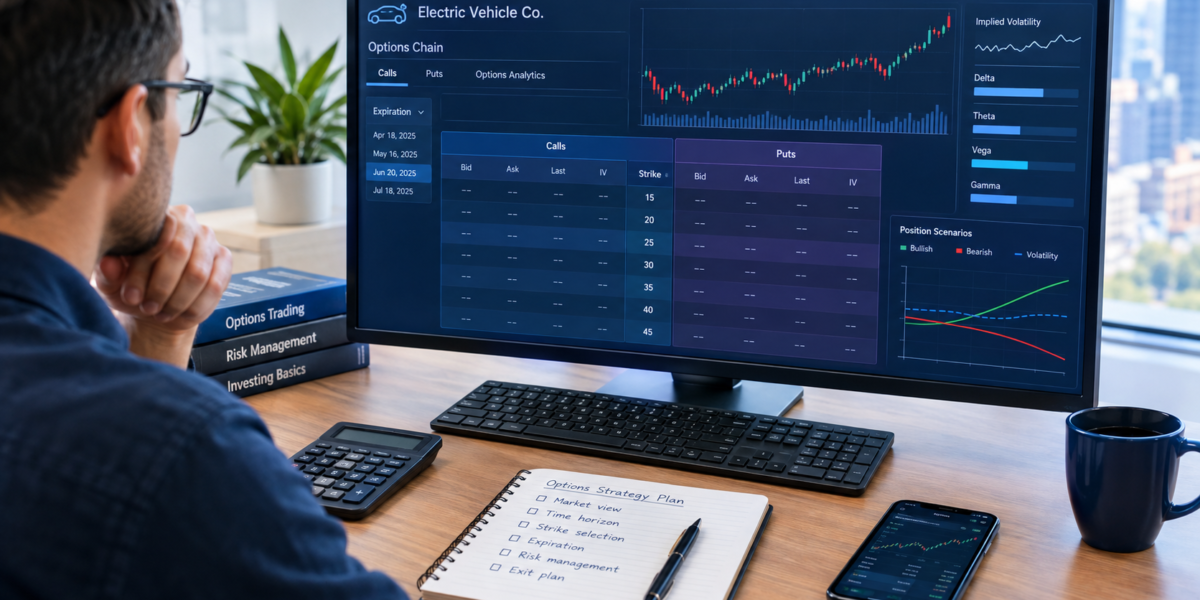
A Lucid Group options trading strategy can give traders several ways to approach LCID depending on their market view, risk tolerance, time horizon, and understanding of options. Instead of simply buying or selling the stock, options allow traders to structure positions around direction, volatility, time decay, or a combination of these factors.
The important point is that an options strategy is not automatically safer or more profitable than buying shares. Options can expire worthless, lose value because of time decay, and become difficult to manage when volatility or liquidity changes. A practical Lucid Group options trading strategy therefore starts with risk management and an understanding of the option contract before considering a particular setup.
Lucid Group is an electric vehicle company whose stock can experience significant price movements. That characteristic can make options interesting to active traders, but it can also increase risk. Historical option activity in LCID has included both calls and puts at different strikes and expirations, demonstrating that traders have used the options market for different directional and volatility views. Historical activity, however, should not be treated as a current trading signal.
What Is a Lucid Group Options Trading Strategy?
A Lucid Group options trading strategy is a structured plan for using calls, puts, or combinations of options on LCID. The strategy normally begins with a market assumption.
For example, a trader might believe that LCID could rise, decline, or remain within a particular range. The trader then selects an options structure that corresponds with that assumption.
A bullish approach could involve a call option or a defined risk call spread. A bearish approach could involve a put or a defined risk put spread. A trader expecting significant movement without knowing the direction could consider a volatility strategy, although such strategies have their own substantial risks.
The strategy also needs to consider expiration, strike price, premium, implied volatility, liquidity, bid ask spread, and time decay. Ignoring these factors can cause a trade to perform differently from what the trader expected even when the underlying stock moves in the anticipated direction for Lucid Group options trading strategy.
Understanding LCID Calls and Puts
Before building a Lucid Group options trading strategy, it is important to understand the two basic option types.
A call option gives the buyer the right, but not the obligation, to buy the underlying shares at the strike price before or at expiration depending on the contract style.
A put option gives the buyer the right, but not the obligation, to sell the underlying shares at the strike price according to the contract terms.
For a trader expecting LCID to rise, a call can provide leveraged exposure to an upward move. However, the call buyer pays a premium and can lose the entire premium if the option expires without sufficient value.
For a trader expecting LCID to decline, a put can provide exposure to a downward move. Again, the premium paid is at risk.
The relationship between the stock price and strike price is known as moneyness. Options can be in the money, at the money, or out of the money. This distinction affects the option’s intrinsic value, premium, and sensitivity to changes in the underlying stock.
Why Options Can Behave Differently From LCID Shares
One of the biggest mistakes beginners make is assuming that an option should rise or fall by the same percentage as the underlying stock.
Options are affected by several variables at the same time. These include the underlying price, time remaining until expiration, implied volatility, interest rates, and the relationship between the strike and stock price.
Delta measures an option’s approximate sensitivity to a change in the underlying stock. Theta represents the effect of time decay. Vega describes sensitivity to changes in implied volatility. Gamma measures how quickly delta can change as the underlying moves.
These Greeks can make an otherwise simple trade more complicated.
For example, LCID could move upward while a call option fails to produce the expected result because the move was too small, expiration was too close, or implied volatility declined. That is why a Lucid Group options trading strategy should evaluate more than direction alone.
Bullish Lucid Group Options Trading Strategy
A bullish trader may believe that LCID has potential to move higher over a defined period. Several approaches can express that view.
One approach is buying a call. This provides a defined maximum loss for the buyer because the premium paid is generally the amount at risk, excluding transaction costs and other circumstances. However, the stock usually needs to move sufficiently in the expected direction before expiration for the position to become profitable.
Another approach is a bull call spread. This involves buying one call and selling another call with a higher strike price and the same expiration. The sold call helps reduce the initial cost but also limits the maximum profit of Lucid Group options trading strategy .
A bull call spread can therefore be useful for a trader who has a bullish view but wants a defined risk structure and is willing to accept capped upside.
The choice between a long call and a call spread depends on the trader’s expectations for the size of the move, the cost of the options, implied volatility, and the desired risk profile.
Nasdaq’s educational material on vertical call spreads notes that strike selection, implied volatility, time decay, liquidity, transaction costs, and position sizing all influence the strategy.
Bearish Lucid Group Options Trading Strategy
A bearish Lucid Group options trading strategy can use puts or put spreads.
Buying a put gives the trader exposure to a decline in LCID while limiting the maximum loss to the premium paid, subject to the contract structure and costs.
A bear put spread can be created by buying a put at one strike and selling another put at a lower strike with the same expiration. The spread limits both potential profit and maximum loss.
A defined risk spread can be easier to quantify than an uncovered short option position. However, the trader still needs to understand expiration, strike selection, liquidity, and the potential effect of implied volatility.
A bearish view also does not guarantee that a put will gain value. LCID could decline after the option has lost substantial time value, or the decline might not be large enough to overcome the premium paid.
Using a Bull Call Spread on LCID
A bull call spread is one possible example of a defined risk Lucid Group options trading strategy.
Suppose a trader expects LCID to move moderately higher rather than making an extremely large move. Instead of buying a single call, the trader could buy a lower strike call and sell a higher strike call with the same expiration.
The maximum loss is generally limited to the net premium paid for the spread.
The maximum profit is generally limited to the difference between the strikes minus the net premium paid.
The breakeven point depends on the lower strike and net premium.
The exact numbers must be calculated using the actual option chain available at the time of the trade. Because option premiums change continuously, historical examples should not be presented as current LCID prices.
This structure can help a trader define risk before entering the position. It does not eliminate risk, however, because the spread can still lose its entire premium.
Using a Bear Put Spread on LCID
A bear put spread is the opposite directional structure.
The trader buys a higher strike put and sells a lower strike put with the same expiration. The position is designed for a decline in the underlying stock.
The maximum loss is generally limited to the net premium paid. The maximum profit is generally limited by the difference between the strikes minus the premium.
The strategy can be considered when a trader expects a decline but wants to avoid paying the full cost of a standalone put.
The tradeoff is that the profit is capped. If LCID falls substantially below the lower strike, the trader does not continue receiving unlimited additional profit from the spread.
This illustrates an important principle in a Lucid Group options trading strategy: reducing the cost or risk of one part of a position often requires accepting another limitation.
Long Straddle and Volatility Based Strategies
Some traders are less concerned about whether LCID rises or falls and instead expect a significant move.
A long straddle involves buying a call and a put with the same strike and expiration. The strategy generally benefits from a sufficiently large move in either direction, but it requires the underlying movement to overcome the combined premium paid.
A major factor is implied volatility.
When implied volatility rises, option prices can increase, while declining implied volatility can hurt long option positions. Time decay can also work against a long straddle as expiration approaches.
Nasdaq’s educational material on straddles identifies underlying price movement, implied volatility, time decay, and strike selection as important dependencies.
A volatility strategy therefore requires more than simply predicting that LCID will move. The trader must consider how much movement may be necessary and whether the options are already pricing in substantial volatility.
Covered Calls and LCID Shares
Investors who already own LCID shares may consider a covered call strategy.
A covered call involves owning shares while selling a call option against those shares. The premium received can provide income, but the seller accepts an obligation to potentially sell the shares at the strike price if the option is exercised or assigned.
The strategy can limit upside participation because the shares may be called away above the strike.
A covered call is therefore different from simply buying a call. The investor already owns the stock and is using an option to change the risk and return profile of the share position.
Before using a covered call as part of a Lucid Group options trading strategy, investors should understand assignment, expiration, dividends if applicable, taxes, and the possibility that the stock could fall substantially while the option premium only partially offsets the decline.
Cash Secured Puts
Another strategy sometimes considered by investors who are willing to own shares is a cash secured put.
The trader sells a put while maintaining enough cash or buying power to purchase the shares if assigned under the contract terms.
The premium received provides income, but it does not eliminate downside risk. If LCID falls significantly below the strike, the trader may face an effective purchase price that is still substantially above the market price after assignment.
A cash secured put should therefore not be viewed as free income.
The trader should only consider a strike and position size they would genuinely be prepared to own under the applicable contract conditions.
Choosing an Expiration Date
Expiration selection is one of the most important parts of a Lucid Group options trading strategy.
Short dated options can provide significant sensitivity to price movements, but they also have limited time for the expected move to occur. Time decay can become especially important as expiration approaches.
Longer dated options provide more time for the thesis to develop but generally cost more and can expose the trader to different volatility and pricing considerations Lucid Group options trading strategy .
There is no universally correct expiration date.
The choice should be connected to the reason for the trade. A short term event based idea may require a different expiration structure from a longer term directional thesis.
Traders should also examine what events could occur before expiration, including company announcements, earnings releases, industry developments, or broader market changes.
Strike Price Selection
Strike selection can substantially change the risk profile of an options position.
An at the money option usually has significant sensitivity to movements in the underlying. Out of the money options may have lower premiums but require a larger move before they become profitable.
Deep in the money options generally contain more intrinsic value and can behave differently from far out of the money contracts.
Choosing a strike solely because the premium appears inexpensive can be dangerous. A low premium may reflect a low probability of reaching the strike before expiration.
A disciplined Lucid Group options trading strategy should therefore evaluate the strike in relation to the expected move rather than choosing the cheapest available contract.
Implied Volatility and LCID Options
Implied volatility is another major consideration.
Implied volatility represents the market’s expectation of future price variability as reflected in option prices. It is not a guarantee of what will happen.
When implied volatility is high, option premiums can become more expensive. A trader who buys options when implied volatility is elevated may face losses if volatility later falls even when the stock moves in the expected direction.
When implied volatility is lower, options can be cheaper, but the market may also be pricing in a smaller expected move.
This creates an important question for any Lucid Group options trading strategy: is the expected stock movement large enough to justify the option premium?
The answer depends on the actual option chain, expiration, strike, market conditions, and the trader’s assumptions.
Liquidity and Bid Ask Spreads
Liquidity should never be ignored.
An option can appear attractive based on its theoretical price but become expensive to enter or exit because of a wide bid ask spread.
The bid is the price buyers are currently offering, while the ask is the price sellers are requesting. The difference between them is the spread.
A wider spread can increase transaction costs and make precise execution more difficult.
Before entering an LCID options position, traders should examine trading volume, open interest, bid ask spread, and available strikes and expirations.
Historical reports have shown substantial options activity in LCID at various points in time, but historical activity should not be interpreted as evidence that the same contracts are liquid today.
Risk Management for a Lucid Group Options Trading Strategy
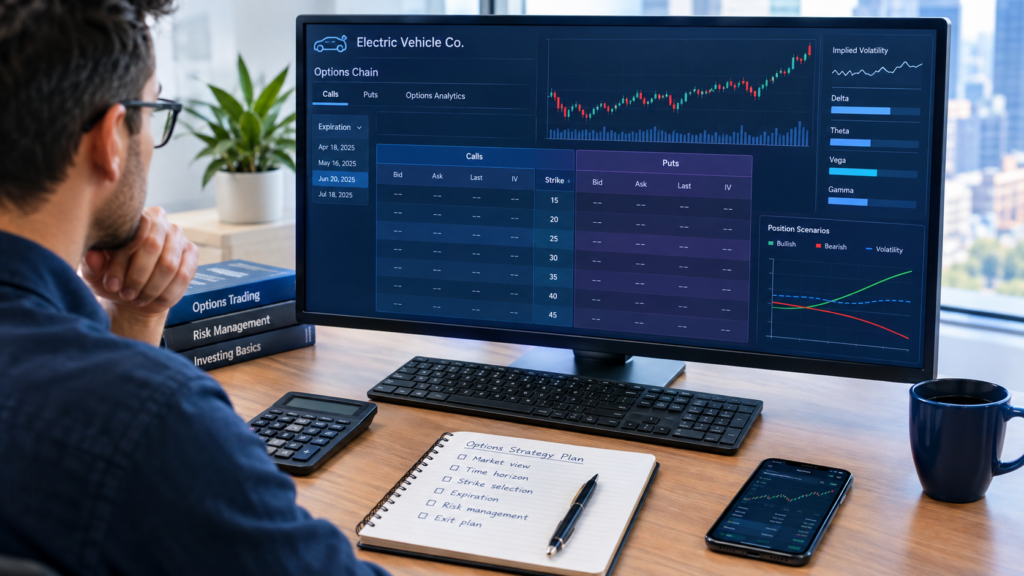
Risk management should be established before entering the position.
One approach is to determine the maximum amount that can be lost and size the trade accordingly Lucid Group options trading strategy.
Defined risk strategies can make this easier because the maximum loss can generally be calculated when the position is opened.
Traders should avoid using money they cannot afford to lose, particularly when dealing with short dated options or highly volatile stocks.
Another important consideration is concentration. A trader who has substantial exposure to LCID shares may already have significant company specific risk. Adding multiple LCID options positions can increase that exposure rather than diversify it.
A risk plan can include:
Position size
Maximum acceptable loss
Entry conditions
Exit conditions
Expiration considerations
Volatility assumptions
Liquidity requirements
Potential assignment or exercise
Transaction costs
Tax considerations
The exact risk limits should be determined according to the individual’s financial circumstances and risk tolerance.
Common Mistakes With LCID Options
A common mistake is buying very cheap out of the money calls because they appear capable of producing large percentage gains. The problem is that the underlying stock may never reach the required price before expiration.
Another mistake is ignoring theta. An option can lose value every day even if the underlying stock does not move significantly.
Some traders also focus only on direction and ignore implied volatility. A correct directional prediction can still produce a poor options result if volatility changes unfavorably Lucid Group options trading strategy.
Another mistake is using excessive position size.
Options provide leverage, which means a relatively small amount of capital can create substantial exposure. That leverage can magnify losses as well as gains.
Finally, traders sometimes hold losing positions simply because they believe the stock will eventually recover. An option has an expiration date, so waiting indefinitely is not possible.
A Simple Process for Building a Lucid Group Options Trading Strategy
A practical process can help reduce impulsive decisions.
First, define the market thesis. Decide whether the expectation is bullish, bearish, neutral, or volatility focused.
Second, define the expected time horizon. Determine when the expected move might occur rather than choosing an expiration randomly.
Third, examine the current option chain. Review strikes, expiration dates, premiums, volume, open interest, implied volatility, and bid ask spreads.
Fourth, compare strategies. A long call, call spread, put, put spread, covered call, cash secured put, or volatility strategy may create very different risk profiles.
Fifth, calculate maximum potential loss before entering.
Sixth, determine what would invalidate the trade thesis.
Seventh, consider transaction costs and liquidity.
Finally, monitor the position rather than assuming that it will automatically behave as expected.
This process does not guarantee a profitable result. Its purpose is to make the trade structure understandable before capital is committed.
Example of Comparing LCID Option Strategies
Consider a hypothetical trader who expects LCID to rise over several months.
A long call offers substantial upside exposure but can lose the entire premium.
A bull call spread reduces the initial cost but limits upside.
A covered call requires ownership of shares and can generate option premium while limiting some upside.
A cash secured put can create an obligation to buy shares at the strike if assigned.
Each structure expresses a different combination of bullish exposure, cost, risk, and obligation.
The appropriate comparison is therefore not simply which strategy can make the most money. A better analysis asks how much can be lost, what needs to happen for the position to work, how much time is available, and whether the trader is comfortable with the obligations created by the strategy.
When an Options Strategy May Not Be Appropriate
There are situations where avoiding an options trade can be a reasonable decision.
If the option chain has poor liquidity, a wide bid ask spread can create unnecessary execution costs.
If the trader does not understand assignment or exercise, selling options can introduce risks that are difficult to manage.
If the expected price movement is uncertain and the premium is high, buying options may expose the trader to substantial time decay and volatility risk Lucid Group options trading strategy.
If the position would represent an excessive percentage of available trading capital, the potential downside may be inappropriate regardless of the strategy.
The ability to identify when not to trade is part of responsible options planning.
How Earnings and Company Events Can Affect LCID Options
Company events can cause rapid changes in stock price and implied volatility.
Earnings announcements, production updates, financing developments, strategic announcements, industry news, and broader EV market developments can all affect investor expectations.
Options traders should identify important scheduled events before selecting an expiration.
A contract that expires immediately after a major event may have very different characteristics from one expiring well before it.
Traders should also avoid assuming that a positive company announcement automatically produces a profitable call position. The market’s expectations may already be reflected in the option premium.
The same principle applies to negative news and put options.
Should Beginners Use a Lucid Group Options Trading Strategy?
Beginners should first learn how options work before risking real money.
Important concepts include calls, puts, strike prices, expiration, premium, intrinsic value, extrinsic value, delta, gamma, theta, vega, implied volatility, assignment, exercise, and liquidity.
Paper trading can allow a person to study how different structures behave without immediately risking capital.
A beginner can also start by comparing hypothetical positions rather than entering multiple strategies at once.
The goal should be understanding how the position behaves under different stock prices and expiration dates.
Options education is particularly important for volatile stocks because price changes can affect premiums quickly.
FAQ
What is a Lucid Group options trading strategy?
A Lucid Group options trading strategy is a planned approach to trading calls, puts, spreads, or other option structures on LCID based on a specific view of price direction, volatility, or time.
Is buying LCID calls risky?
Yes. A call buyer can lose the premium paid if the option expires without sufficient value. The risk is particularly important with short dated or out of the money contracts.
What is a bull call spread on LCID?
A bull call spread generally involves buying one call and selling another call with a higher strike price and the same expiration. It can reduce the initial cost compared with buying a call but limits maximum profit.
What is a bear put spread?
A bear put spread generally involves buying a higher strike put and selling a lower strike put with the same expiration. It is designed for a bearish view with defined maximum risk based on the spread structure.
Why does implied volatility matter for LCID options?
Implied volatility affects option premiums. A change in implied volatility can affect the value of an option even when LCID itself moves in the expected direction.
How does time decay affect LCID options?
Time decay reduces the value of an option’s time component as expiration approaches. This can be particularly important for options with limited time remaining.
Should I trade LCID options before earnings?
That depends on the strategy, risk tolerance, option pricing, and expected volatility. Traders should understand that major events can produce rapid price and implied volatility changes.
Can a Lucid Group options trading strategy guarantee profit?
No. Options strategies cannot guarantee profits. Every strategy has specific risks, costs, and conditions that can lead to losses.
Final Takeaway
A Lucid Group options trading strategy should be built around a clearly defined market view, time horizon, risk limit, option structure, strike, expiration, volatility assumption, and liquidity check.
There is no single strategy that works in every LCID market environment. Long calls and puts provide directional exposure, vertical spreads can define risk and limit potential profit, covered calls can modify an existing share position, and volatility strategies can target large price movements. Each structure has different costs, obligations, and risks.
The most important step is understanding the complete position before entering it. Traders should calculate the potential loss, understand time decay, examine implied volatility and liquidity, and avoid relying on historical options activity as a current signal.
Current LCID option prices, strikes, volume, and implied volatility should always be checked directly in a live options chain before making a trading decision. Options involve substantial risk and are not suitable for every investor.
You may also find blog on below
ADP Payroll Services for Small Business
Related Wealth Articles
American First Finance: A Complete Guide to Payment Options, Costs, and Customer Considerations
What Is American First Finance? American First Finance is a consumer financing company that offers payment solutions through…
Capital One Customer Service 24/7 Phone Number: How to Get Help
Finding the Capital One customer service 24/7 phone number can help you determine how to contact the company…