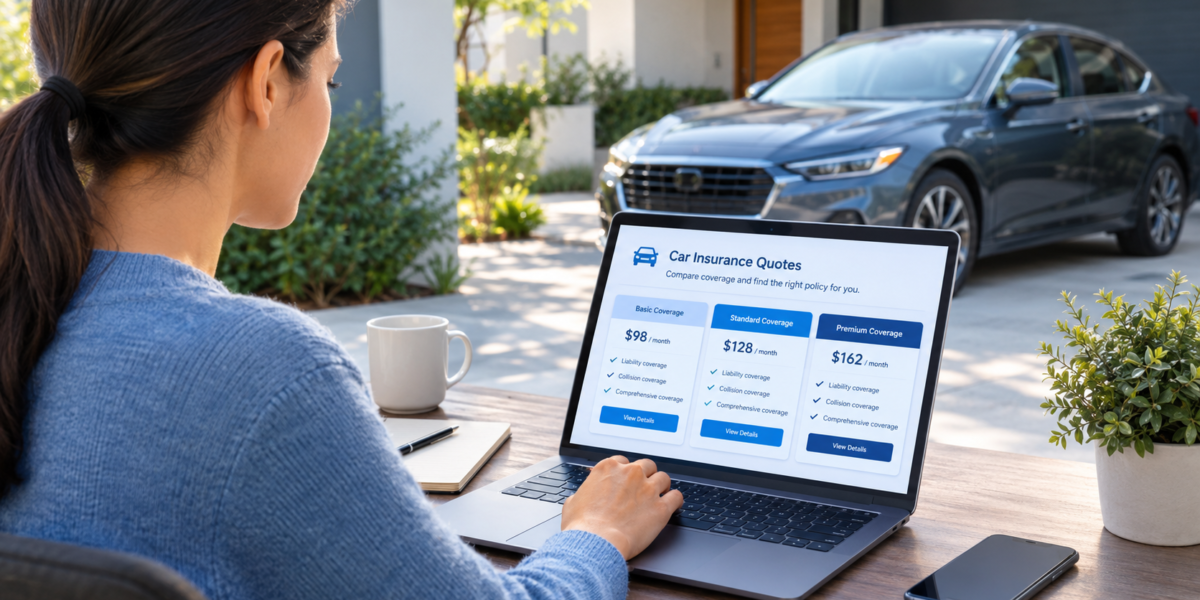
Car Insurance Quotes: How to Compare Coverage and Costs
Getting car insurance quotes is one of the simplest ways to see how different insurers may price coverage for the same driver and vehicle. However, comparing quotes is not simply about finding the smallest number on the screen. A cheaper quote may provide lower coverage limits, higher deductibles, or fewer optional protections.
The useful comparison is between policies that provide similar coverage. Insurance regulators and industry consumer organizations recommend comparing coverage, limits, deductibles, policy terms, and the insurer itself rather than choosing based on price alone.
The exact insurance requirements differ by country and, in some places, by state or province. Your driving history, location, vehicle, mileage, selected coverage, deductible, and other factors can also affect the premium.
What Are Car Insurance Quotes?
A car insurance quote is an estimated price an insurer provides for a particular level of vehicle insurance coverage based on information supplied by the applicant. It is generally based on details such as the vehicle, drivers, location, driving history, intended vehicle use, selected coverages, and deductibles.
A quote is not necessarily the same as the final amount you will pay. An insurer may need to verify information before coverage is finalized, and the final premium can depend on underwriting and rating rules applicable to your situation.
Insurance companies assess risk differently, so two insurers can offer different prices for similar coverage. The National Association of Insurance Commissioners explains that auto insurance pricing involves underwriting and rating, with factors such as location, age, driving experience, driving record, claims history, vehicle type, mileage, coverage selections, and deductibles potentially affecting premiums.
This is why obtaining several car insurance quotes can be useful. It gives you a clearer picture of the range of prices available to you and helps identify differences in coverage.
Why Should You Compare Car Insurance Quotes?
Insurance companies do not necessarily charge the same price for the same driver and Car Insurance Quotes. Their underwriting models, rating factors, coverage options, discounts, and pricing structures can differ.
Comparing quotes can help you:
• Identify differences in premiums
• Compare coverage limits
• Understand deductible differences
• Find optional coverage that may be useful
• Check whether discounts are available
• Review payment options
• Evaluate different insurers before purchasing
The Insurance Information Institute recommends comparing policies from multiple insurers and emphasizes that coverage should be compared on an equivalent basis.
For example, imagine one insurer quotes a lower premium but uses a higher collision deductible and lower liability limits. Another insurer charges more but provides higher limits and additional protections. Looking only at the premium would not provide a complete comparison.
What Information Do You Need for Car Insurance Quotes?
Before requesting car insurance quotes, collect accurate information. Having the same information available for each quote makes comparisons easier.
You may need information about:
Driver Information
Insurers commonly ask for information about the drivers who will be covered. This may include age, driving experience, license information, driving history, and claims history.
If multiple people regularly drive the vehicle, make sure the quote accurately reflects the drivers who need to be covered. The NAIC advises consumers to include relevant drivers when requesting quotes and to provide complete information.
Vehicle Information
You may need the vehicle identification number, make, model, year, registration information, and details about how the vehicle is used.
The vehicle itself can influence insurance pricing. Repair costs, vehicle characteristics, safety features, theft risk, and other factors can affect how insurers evaluate risk.
Driving History
Tickets, accidents, claims, and other driving history information can affect the price of coverage. Insurers may obtain driving information through records and other sources as part of their underwriting process.
Vehicle Use and Mileage
Tell the insurer how the vehicle is actually used. Driving to work, personal use, business use, delivery work, and other uses may have different insurance implications.
Annual mileage can also be a rating factor. Some insurers offer usage based or mileage related insurance programs, although availability and terms vary by market.
What Coverage Should You Compare?
The most important part of comparing car insurance quotes is understanding what each policy actually covers.
Liability Coverage
Liability insurance generally helps cover certain costs when an insured driver is legally responsible for injuries or property damage caused to another party, subject to the policy terms and limits.
Many jurisdictions require some form of liability coverage, but the minimum requirements vary. Minimum legal coverage may not necessarily provide the level of financial protection a driver wants.
When comparing quotes, look at the liability limits rather than only the premium.
Collision Coverage
Collision coverage generally applies to damage to the insured vehicle resulting from covered collisions, subject to policy terms and a deductible.
A lender or leasing company may require collision coverage when a vehicle is financed or leased.
Comprehensive Coverage
Comprehensive coverage generally addresses certain damage to the vehicle that is not caused by a collision, such as specified theft, fire, or weather related events, depending on the policy.
Like collision coverage, comprehensive coverage commonly has a deductible.
Uninsured or Underinsured Motorist Coverage
Depending on the jurisdiction and policy, uninsured or underinsured motorist coverage can provide protection when another responsible driver has insufficient or no insurance.
The availability, requirements, and exact benefits vary by location, so review the policy wording and local requirements.
Medical or Personal Injury Coverage
Some insurance systems provide medical payments coverage or personal injury protection. These coverages can help with certain injury related expenses, depending on the policy and applicable law.
Because these rules vary significantly between jurisdictions, consumers should check their local insurance requirements.
Optional Coverage
Insurers may offer additional protections such as rental vehicle reimbursement, roadside assistance, towing, glass coverage, or other options.
Optional coverage can increase the premium, so consider whether the protection fits your circumstances instead of adding every available feature automatically.
How Do Insurers Determine Car Insurance Prices?
There is no single factor that determines every car insurance premium. Insurers can consider multiple rating factors, and the rules differ by jurisdiction.
Common factors can include:
• Location
• Driving record
• Claims history
• Age and driving experience
• Vehicle type
• Vehicle use
• Annual mileage
• Selected coverage
• Deductibles
• Previous insurance coverage
• Credit based insurance information where permitted
• Other legally permitted rating factors
The NAIC identifies many of these factors in its consumer guidance on auto insurance.
Location
Where you live and where the vehicle is normally kept can affect insurance pricing. Local accident frequency, theft, repair costs, claims patterns, and insurance regulations can all influence rates.
Driving Record
A history of traffic violations or crashes may affect how an insurer evaluates risk. The effect can vary between companies and jurisdictions.
Vehicle Type
A vehicle that is expensive to repair or replace can have different insurance costs from a less expensive vehicle. Safety characteristics, repair costs, theft patterns, and claims experience may also matter of Car Insurance Quotesm.
Mileage
Someone who drives significantly more may have more exposure to road risks than someone who drives only occasionally. Mileage is therefore one factor some insurers use when calculating premiums.
Deductible
A deductible is the amount you are responsible for paying toward a covered claim before the insurer pays its portion, subject to policy terms.
Generally, selecting a higher deductible can reduce the premium, but it also means you may have to pay more yourself after a covered loss.
A deductible should therefore be chosen based on what you could realistically afford after an unexpected incident.
How to Compare Car Insurance Quotes Properly
The most effective comparison is to make the quotes as similar as possible.
Step 1: Decide What Coverage You Need
Start by understanding your legal requirements and your personal financial needs. If your vehicle is financed or leased, check whether the lender has additional insurance requirements.
Do not begin by choosing the cheapest possible coverage. First establish the protection you need, then compare prices for that protection.
Step 2: Request Several Quotes
Obtain quotes from multiple insurers. You can contact insurers directly, use online comparison services where available, or work with an insurance agent.
The NAIC notes that some online services provide quotes from multiple companies, while others connect consumers with agents or individual insurers.
Step 3: Use Matching Coverage
This is one of the most important steps.
If one quote has higher liability limits, a lower deductible, and more optional coverage than another quote, the two prices are not directly comparable.
Create a simple comparison showing:
| Comparison factor | Quote A | Quote B | Quote C |
| Coverage limits | Same limits | Same limits | Same limits |
| Collision deductible | Same | Same | Same |
| Comprehensive deductible | Same | Same | Same |
| Optional coverage | Same where needed | Same where needed | Same where needed |
| Premium | Compare | Compare | Compare |
| Payment schedule | Compare | Compare | Compare |
Using matching coverage helps you understand whether a lower price actually represents a similar insurance package. The NAIC specifically recommends asking insurers to provide revised estimates when quotes do not have matching coverage and limits.
Step 4: Check Discounts
Ask each insurer which discounts may apply to your situation.
Potential discounts can vary widely by insurer and jurisdiction. They may relate to factors such as multiple policies, vehicle safety features, driving behavior, payment arrangements, or other qualifying circumstances.
Never assume that a discount advertised by one insurer will be available from another insurer.
Step 5: Review the Deductibles
A quote with a lower premium may have a higher deductible.
For example, reducing the premium by accepting a larger deductible could make sense for someone who has enough emergency savings to cover that deductible. It may be less suitable for someone who would struggle to pay it after an accident.
The important question is not simply whether the deductible is high or low. It is whether the deductible and premium combination fits your financial situation.
Step 6: Research the Insurer
Price is important, but the insurer also matters.
Check whether the insurer is licensed in the relevant jurisdiction and look for available information about complaints, financial strength, and claims service. Consumer insurance organizations recommend checking state or local insurance regulators where applicable.
Online Car Insurance Quotes Versus Working With an Agent
There are several ways to obtain car insurance quotes.
Online Quotes
Online quoting can be convenient because you can enter information from your computer or phone and compare available options of Car Insurance Quotes.
However, the information displayed online should still be reviewed carefully. Some comparison services may connect you with agents instead of providing a final policy directly, and not every website provides an immediate binding quote.
Direct Insurer Quotes
You can also request a quote directly from an insurance company. This may provide detailed information about that company’s available coverage and pricing.
The limitation is that you may need to repeat your information when comparing several companies.
Independent Insurance Agents
An independent agent may represent multiple insurers and can potentially provide quotes from more than one company. An exclusive agent generally represents one insurer.
The NAIC describes independent agents as representatives of several companies, while exclusive agents sell products from one insurance company.
The best method depends on how you prefer to shop and how much assistance you want.
Why the Cheapest Car Insurance Quote May Not Be the Right Comparison
A low premium can be attractive, but price alone does not tell you how much protection a policy provides.
Consider two hypothetical quotes.
Quote A costs less but has a higher deductible and lower liability limits.
Quote B costs more but has higher liability limits and a lower deductible.
Neither quote can be meaningfully judged by premium alone because the policies transfer different amounts of financial risk to the driver.
This is why comparing equivalent coverage is so important.
You should also check exclusions, conditions, optional benefits, payment fees, cancellation terms, and other policy details before purchasing.
Ways to Potentially Lower Your Car Insurance Costs
There are several legitimate ways to explore lower premiums without simply removing important protection.
Compare Multiple Insurers
Shopping around can reveal price differences between insurers. The Insurance Information Institute recommends obtaining multiple quotes because premiums can vary significantly between companies.
Ask About Available Discounts
Ask insurers to identify discounts for which you may qualify. Do not assume that every discount is automatically applied.
Review Your Deductible
If financially appropriate, a higher deductible may reduce the premium. Before making the change, make sure you could afford the deductible if you needed to make a claim.
Review Your Coverage Regularly
Your insurance needs can change when you buy another vehicle, add or remove a driver, change how much you drive, or experience another major change in circumstances.
The NAIC recommends periodically reviewing policy information and updating it when relevant circumstances change.
Consider Vehicle Insurance Costs Before Buying
Insurance is part of the ongoing cost of owning a vehicle. If you are deciding between vehicles, obtaining car insurance quotes before purchasing can help you understand the potential insurance cost.
A vehicle with a lower purchase price is not necessarily the vehicle with the lowest total ownership cost.
Should You Get New Car Insurance Quotes Every Year?
Car Insurance Quotes is no universal rule requiring every driver to obtain new quotes at a specific interval, but periodically reviewing your insurance can be useful.
Premiums and personal circumstances can change. You may have a different vehicle, different mileage, additional drivers, a changed driving record, or different coverage needs.
You can also ask your existing insurer whether your current policy still reflects your circumstances.
When comparing a new quote with your existing policy, make sure the coverage limits and deductibles are comparable.
What Can Make a Quote Change?
A quote may change when information provided during the application changes or when an insurer verifies information.
Potential examples include:
• A different vehicle
• A different driver
• A change in annual mileage
• A change in address
• A new accident or traffic violation
• A change in coverage limits
• A different deductible
• A change in vehicle use
• Newly available discounts
Insurance pricing is based on risk assessment and rating rules, so the exact effect of a change depends on the insurer and jurisdiction.
Common Mistakes When Comparing Car Insurance Quotes
Comparing Only the Premium
This is the most obvious mistake. A premium is only one part of the policy.
Comparing Different Coverage Levels
A lower quote may simply provide less coverage.
Choosing a Deductible Without Considering Your Budget
A deductible that looks attractive because it reduces the premium may become difficult to manage after a claim.
Providing Incomplete Information
Accurate information is important when requesting quotes. Incorrect or incomplete information can create problems when the insurer verifies the application or processes a claim.
Ignoring Policy Exclusions
A policy does not cover every possible event. Read the policy documents and understand important exclusions and conditions.
Forgetting About Vehicle Use
Using a personal vehicle for certain paid activities may require different insurance arrangements. The Insurance Information Institute notes that personal auto insurance may not provide the necessary coverage for certain commercial activities.
Focusing Only on Online Reviews
Reviews can provide useful experiences, but they should not be treated as a complete assessment of an insurer. Consider regulatory information, policy terms, financial strength information, and your own coverage requirements as well.
Questions to Ask Before Buying a Policy
Before accepting a quote, consider asking:
- What coverage limits are included?
- What are the collision and comprehensive deductibles?
- What exclusions should I understand?
- Which drivers are covered?
- Is my normal vehicle use covered?
- Are there optional protections that may be useful for my situation?
- Are any discounts included in the quoted price?
- Is there a fee for paying monthly?
- What happens if I change vehicles?
- How do I file a claim?
- Is the insurer licensed in my jurisdiction?
- Can I review the full policy documents before purchasing?
These questions can help you move beyond a simple price comparison and understand what you are actually buying.
Car Insurance Quotes and Credit Information
In some jurisdictions, insurers may use credit based insurance information as one factor in underwriting or rating auto insurance. This is not the same thing as using a credit score to determine whether someone can repay a loan.
The rules governing this practice vary by jurisdiction. The NAIC’s current consumer information explains that credit based insurance scores are used in places where the practice is legally permitted.
If this factor concerns you, check the rules that apply where you live and ask the insurer how it is used.
Usage Based Car Insurance
Some insurers offer usage based insurance programs that use telematics to collect information about driving behavior or vehicle use.
Depending on the program, information may include mileage, acceleration, braking, time of day, or other driving behavior.
These programs can involve privacy considerations as well as pricing considerations. Before enrolling, understand what information is collected, how it is used, how long it is retained, and how participation can affect your premium under that particular program.
What Should You Do After Finding a Quote?
Once you identify a quote that appears suitable, do not immediately pay based only on the headline price.
Review the coverage details, limits, deductibles, exclusions, payment schedule, effective date, and policy documents.
Make sure the information submitted is accurate.
If you are replacing an existing policy, confirm when the new coverage becomes effective before cancelling the old policy. Avoid creating an unintended gap in coverage.
Keep copies of your policy documents and insurance identification information in an accessible place.
FAQ
How many car insurance quotes should I compare?
There is no universal required number, but comparing several insurers can show how prices and coverage options differ. The Insurance Information Institute recommends obtaining quotes from at least three insurers when shopping for auto insurance.
Why are car insurance quotes different between companies?
Insurers use their own underwriting and rating processes. They may evaluate factors such as location, driving history, vehicle, mileage, claims history, coverage choices, and deductibles differently, subject to applicable law.
Is the cheapest car insurance quote always the best option?
A lower premium may come with different coverage limits, higher deductibles, or fewer optional protections. Compare policies using similar coverage before judging the price.
What information is needed to get car insurance quotes?
Depending on the insurer and jurisdiction, you may need driver information, vehicle details, driving history, claims information, current insurance details, registration information, and information about how and how much the vehicle is used.
Does a higher deductible reduce car insurance costs?
Generally, selecting a higher deductible can reduce the premium for applicable coverage, but you would be responsible for a larger amount when a covered claim requires you to pay the deductible.
Can I get car insurance quotes online?
Many insurers and comparison services provide online quoting options, although availability and the quoting process vary by jurisdiction and company. Some online services may involve an agent or require additional verification before coverage is finalized.
Can my driving record affect my quote?
Yes. Driving records can be used as a rating factor, although the exact effect varies by insurer and jurisdiction. Traffic violations and crashes may affect how an insurer evaluates risk.
Should I compare car insurance quotes when buying another car?
Yes. Obtaining insurance quotes before purchasing a vehicle can help you understand the potential insurance cost as part of the overall cost of ownership. Vehicle type and repair or replacement costs can influence premiums.
Final Takeaway
Car insurance quotes are useful comparison tools, but the lowest number is not necessarily the most meaningful result. A proper comparison looks at coverage limits, deductibles, exclusions, optional protections, payment terms, insurer information, and overall suitability.
Start by understanding the coverage you need. Then request several quotes using consistent information and comparable limits. Review the deductible carefully and ask about discounts that genuinely apply to you.
Insurance requirements and pricing rules vary by jurisdiction, so verify current requirements with the relevant insurance regulator or insurer before purchasing. The goal of comparing car insurance quotes is not simply to find a number that looks low. It is to understand what each price represents and choose coverage that fits your circumstances and budget.
You may also find blog on below
Travel Health Insurance
Related Wealth Articles
Whole Life Insurance: How It Works, Benefits, Costs and Risks
Whole life insurance is a type of permanent life insurance designed to provide coverage for the insured person’s…
Progressive Insurance Phone Number: Customer Service and Claims Guide
Progressive Insurance Phone Number: Quick Answer If you are looking for the Progressive Insurance phone number, Progressive currently…
1 Discussion Comment