Working Capital Management Tutorial Explained: A Complete Guide
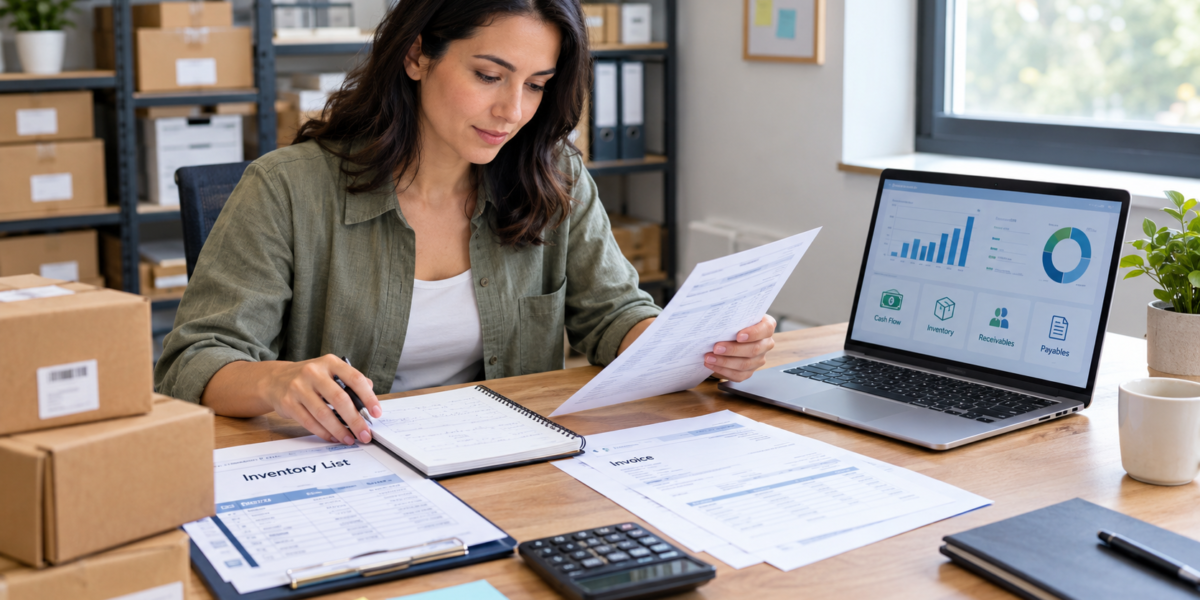
Working capital management is an essential part of running a financially healthy business. It helps companies manage their short-term assets and liabilities, maintain sufficient cash, pay suppliers on time, and meet everyday operating expenses. Without proper management, even a profitable business can experience financial difficulties because its money may be tied up in inventory or unpaid customer invoices.
This working capital management tutorial explained guide covers the meaning of working capital, its main formulas, practical calculations, important techniques, common mistakes, and ways to improve business cash flow. Whether you are a student, entrepreneur, accountant, or business owner, understanding these concepts can help you make better financial decisions.
Table of Contents
What Is Working Capital Management?
Working capital management is the process of managing a company’s current assets and current liabilities to support daily business operations. Current assets generally include cash, accounts receivable, and inventory. Current liabilities include short-term obligations such as supplier payments, accrued expenses, and certain short-term borrowings.
The primary objective is to maintain enough liquidity to meet financial obligations without keeping excessive money tied up in assets that could be used more productively.
For example, a retailer may have plenty of products in its warehouse but insufficient cash to pay employees or suppliers. Effective working capital management helps the retailer balance inventory purchases, customer payments, and operating expenses.
It is important to understand that working capital management is not simply about increasing cash. It involves finding a suitable balance between liquidity, profitability, operational efficiency, and financial risk.
What Is Working Capital?
Working capital is the difference between a company’s current assets and current liabilities. It provides a basic indication of whether a business has sufficient short-term resources to cover its short-term obligations.
The formula is:
Net Working Capital = Current Assets − Current Liabilities
For example, suppose a business has the following financial position:
- Cash: $15,000
- Accounts receivable: $20,000
- Inventory: $25,000
- Current liabilities: $35,000
Total current assets equal $60,000.
Net working capital = $60,000 − $35,000 = $25,000.
The business has positive working capital of $25,000.
Positive working capital can indicate that a company has more current assets than current liabilities. However, it does not automatically mean the company has enough cash available. Some inventory may be difficult to sell, and some customer invoices may be overdue.
Negative working capital means current liabilities exceed current assets. Depending on the business model, this can indicate financial pressure, although certain businesses with rapid cash collection and favorable supplier terms can operate successfully with negative working capital.
Why Is Working Capital Management Important?
Effective working capital management supports the day-to-day financial stability of a business. It helps management understand when money will enter the business, when payments are due, and how much cash must remain available.
Its main benefits include:
1. Maintaining Sufficient Cash Flow
Businesses need cash to pay wages, rent, utilities, suppliers, and other operating expenses. Monitoring incoming and outgoing cash helps reduce the risk of payment delays.
2. Improving Operational Efficiency
Managing inventory and customer payments effectively reduces the amount of money tied up in daily operations. This can make funds available for other business needs.
3. Reducing Short-Term Financial Pressure
Businesses that plan their cash requirements can identify potential shortages earlier and consider appropriate solutions before payments become overdue.
4. Supporting Business Growth
Expansion often requires additional inventory, staff, equipment, and customer credit. Working capital planning helps businesses estimate these needs before committing to growth.
5. Strengthening Supplier Relationships
Paying suppliers according to agreed terms can support reliable business relationships and help avoid unnecessary penalties or disruptions.
Key Formulas Used in Working Capital Management
Understanding the main formulas makes working capital management easier to apply in real business situations.
Net Working Capital Formula
Net Working Capital = Current Assets − Current Liabilities
This calculation measures the difference between short-term assets and short-term obligations.
Current Ratio Formula
Current Ratio = Current Assets ÷ Current Liabilities
Suppose a company has current assets of $80,000 and current liabilities of $40,000.
Current ratio = $80,000 ÷ $40,000 = 2.0.
This means the company has $2 in current assets for every $1 in current liabilities. A ratio of 2.0 is not automatically ideal for every business because appropriate levels vary by industry, asset quality, and operating cycle.
Quick Ratio Formula
Quick Ratio = (Cash + Short-Term Investments + Accounts Receivable) ÷ Current Liabilities
This ratio excludes inventory and certain other less liquid current assets. It helps assess whether a company can cover short-term obligations using assets that are generally more readily convertible into cash.
Inventory Turnover Ratio
Inventory Turnover = Cost of Goods Sold ÷ Average Inventory
This formula measures how frequently inventory is sold and replaced over a period. A very low turnover rate may indicate excess stock or weak demand, while an unusually high rate could indicate insufficient inventory.
Accounts Receivable Days
Accounts Receivable Days ≈ (Average Accounts Receivable ÷ Credit Sales) × Number of Days in the Period
This calculation estimates how long a business takes to collect payment from credit customers. The period used should match the sales figures, and interpretation should account for payment terms and seasonal changes.
Main Components of Working Capital Management
Working capital management focuses on several interconnected areas of business finance.
Cash Management
Cash management involves monitoring available funds, forecasting cash requirements, and scheduling payments appropriately. Businesses should maintain enough accessible cash to cover expected expenses and unexpected shortfalls.
A rolling cash flow forecast can help management estimate cash inflows and outflows over the coming weeks or months.
Inventory Management
Inventory management aims to maintain sufficient stock to meet customer demand without tying up excessive funds in unsold goods.
Businesses can use sales forecasts, reorder points, inventory tracking, and regular stock reviews to reduce overstocking and shortages.
Accounts Receivable Management
Accounts receivable represents money customers owe for goods or services already supplied on credit.
Companies can improve collections by setting clear payment terms, checking customer creditworthiness where appropriate, sending invoices promptly, and following up on overdue accounts professionally.
Accounts Payable Management
Accounts payable represents amounts a business owes to suppliers and other creditors.
Businesses should plan payments around agreed due dates and take advantage of supplier credit terms when commercially appropriate. Delaying payments beyond agreed terms can damage supplier relationships or result in additional costs.
Practical Example of Working Capital Management
Consider a small wholesale business with the following monthly financial information:
Current assets:
- Cash: $10,000
- Accounts receivable: $30,000
- Inventory: $40,000
Total current assets: $80,000.
Current liabilities: - Accounts payable: $25,000
- Short-term loan obligations: $15,000
Total current liabilities: $40,000.
Net working capital = $80,000 − $40,000 = $40,000.
Current ratio = $80,000 ÷ $40,000 = 2.0.
At first glance, the business appears to have a reasonable short-term asset position. However, its $40,000 inventory balance may not be immediately convertible into cash, and the $30,000 in receivables may include invoices that are not yet due.
Management could review overdue invoices, identify slow-moving inventory, forecast upcoming supplier payments, and maintain an appropriate cash reserve.
The objective is not simply to increase the working capital figure. It is to ensure that the company’s resources are available when its obligations fall due.
Effective Working Capital Management Techniques
Businesses can improve their working capital position through consistent monitoring and practical financial controls.
Prepare a Cash Flow Forecast
Estimate expected customer receipts, supplier payments, payroll, taxes, rent, loan payments, and other operating expenses. Update the forecast regularly when actual results differ from expectations.
Improve Customer Collections
Send accurate invoices promptly, communicate payment terms clearly, and follow up on overdue balances. Review credit policies when customers repeatedly pay late.
Control Inventory Levels
Use demand forecasts and stock reports to identify products that sell slowly. Avoid purchasing more inventory than the business can reasonably sell or store.
Review Supplier Payment Terms
Compare supplier terms and payment schedules with expected cash receipts. Where appropriate, negotiate mutually acceptable payment terms rather than missing due dates.
Monitor Financial Ratios
Track net working capital, the current ratio, the quick ratio, inventory turnover, and collection periods over time. Compare results with previous periods and relevant industry benchmarks.
Maintain an Appropriate Cash Reserve
Keep sufficient accessible funds to manage routine expenses and unexpected events. The appropriate reserve depends on business size, cash flow stability, payment obligations, and access to financing.
Common Working Capital Management Mistakes
Poor working capital management can create cash shortages even when sales are growing.
One common mistake is focusing only on sales revenue. Higher sales can increase inventory purchases and customer receivables, creating additional cash requirements before payments arrive.
Another mistake is allowing overdue invoices to accumulate. When customers take longer to pay, the business may struggle to cover its own obligations.
Excessive inventory is also a concern because unsold products tie up cash and may become obsolete, damaged, or difficult to sell.
Some businesses also pay suppliers too early without considering their cash requirements, while others delay payments beyond agreed terms and risk damaging important relationships.
Finally, relying on a single financial ratio can lead to poor decisions. Ratios should be interpreted alongside cash flow forecasts, asset quality, payment schedules, and the company’s operating cycle.
Working Capital Management vs. Cash Flow Management
Working capital management and cash flow management are related, but they are not identical.
Working capital management focuses on current assets and current liabilities, including inventory, receivables, payables, and short-term liquidity.
Cash flow management focuses on the timing and movement of cash entering and leaving a business.
For example, a company may report positive net working capital because it has substantial inventory and unpaid invoices. However, it may still face a cash shortage if supplier payments are due before customers pay.
Using both approaches gives management a clearer picture of short-term financial health.
How to Create a Working Capital Management Plan
A practical plan does not need to be complicated. The following steps provide a useful starting point.
- Review current assets and current liabilities to establish the business’s current working capital position.
- Prepare a cash flow forecast covering expected receipts and payments.
- Identify the main causes of cash being tied up, such as slow collections, excess inventory, or unfavorable payment terms.
- Set realistic targets for collection periods, stock levels, payment scheduling, and available cash.
- Assign responsibility for monitoring each area and establish a regular reporting schedule.
- Compare actual results with forecasts and adjust the plan when business conditions change.
Review the plan regularly, especially during periods of rapid growth, seasonal demand, rising costs, or uncertain customer payments.
FAQ SECTION
What is working capital management in simple words?
Working capital management is the process of managing a company’s short-term assets and liabilities so it can pay its bills, operate efficiently, and maintain sufficient liquidity.
What is the main objective of working capital management?
The main objective is to maintain an appropriate balance between liquidity, profitability, and operational efficiency while ensuring short-term financial obligations can be met.
What is the formula for working capital?
Net working capital is calculated by subtracting current liabilities from current assets.
What are the four main components of working capital management?
The four main components are cash management, inventory management, accounts receivable management, and accounts payable management.
Is positive working capital always good?
Not necessarily. Positive working capital can indicate short-term financial flexibility, but its usefulness depends on whether assets are liquid, inventory is saleable, and receivables can be collected on time.
How can a small business improve working capital?
A small business can improve working capital by forecasting cash flow, collecting invoices promptly, controlling inventory, reviewing supplier terms, and monitoring short-term financial obligations.
What is the difference between working capital and working capital management?
Working capital is the difference between current assets and current liabilities. Working capital management is the process of managing those assets and liabilities to support daily business operations.
Final Thoughts
Working capital management helps businesses balance liquidity, operational efficiency, and profitability. By managing cash, inventory, receivables, and payables together, companies can improve their ability to meet short-term obligations and support sustainable operations.
The most useful approach combines accurate financial records, regular cash flow forecasting, sensible credit policies, and ongoing monitoring of working capital ratios. No single formula tells the whole story, so businesses should consider the quality of their assets and the timing of their liabilities before making decisions.
For students and business owners learning these concepts, the key lesson is simple: a financially healthy business needs not only sales and profits but also the right amount of cash available at the right time.
You my also find blog on below
Capital One Auto Finance: How Loans, Payments, and Prequalification Work
Related Wealth Articles
American First Finance: A Complete Guide to Payment Options, Costs, and Customer Considerations
What Is American First Finance? American First Finance is a consumer financing company that offers payment solutions through…
Capital One Customer Service 24/7 Phone Number: How to Get Help
Finding the Capital One customer service 24/7 phone number can help you determine how to contact the company…
1 Discussion Comment