Marketplace Health Insurance: A Practical Guide to Plans, Costs, and Enrollment
If you need individual or family health coverage in the United States, marketplace health insurance can provide a way to compare health plans and apply for financial assistance. The Health Insurance Marketplace allows eligible people to review available plans, compare coverage and costs, and enroll in qualifying health insurance.
For 2026 coverage, HealthCare.gov allows consumers to preview available plans and estimated prices based on factors such as ZIP code, household size, and estimated income. The exact premium and available savings depend on the information in your application and the plans available in your area.
What Is Marketplace Health Insurance?
Marketplace health insurance is coverage purchased through the Health Insurance Marketplace created under the Affordable Care Act, commonly called the ACA.
The federal Marketplace is operated through HealthCare.gov, while some states operate their own Marketplace websites. Through the Marketplace, eligible consumers can compare health plans, check whether they qualify for financial assistance, and enroll in coverage.
Marketplace coverage is generally designed for people who do not have suitable health insurance through an employer or another government program.
Plans offered through the Marketplace must cover essential health benefits and include protections for people with pre-existing conditions.
How Does Marketplace Health Insurance Work?
The process is relatively straightforward.
First, you provide information such as your ZIP code, household members, and estimated household income. The Marketplace Health Insurance uses this information to determine which plans and potential savings may be available to you.
You can then compare plans based on factors such as:
• Monthly premium
• Deductible
• Copayments
• Coinsurance
• Out-of-pocket maximum
• Provider network
• Prescription drug coverage
• Covered services
After selecting a plan, you complete enrollment and pay your premium directly to the insurance company. Coverage generally does not begin until the required first premium has been paid.
The Marketplace can also determine whether you may qualify for Medicaid, CHIP, or financial assistance with Marketplace coverage.
Who Can Get Marketplace Health Insurance?
Marketplace eligibility depends on your circumstances.
Generally, you must live in the United States, be a U.S. citizen or national or be lawfully present, and not be incarcerated. People enrolled in Medicare generally cannot enroll in a Marketplace health or dental plan.
Eligibility for financial assistance is a separate question. Someone may be eligible to purchase Marketplace coverage but receive little or no financial assistance depending on household income and access to other qualifying coverage.
Your eligibility can also change after events such as a change in income, household size, employment, or access to employer-sponsored insurance.
How Much Does Marketplace Health Insurance Cost?
There is no single price for marketplace health insurance.
Your cost can depend on:
• Where you live
• Your age
• Household size
• Estimated household income
• The plan you choose
• The insurance company offering the plan
• Whether you qualify for financial assistance
• Whether you qualify for additional cost-sharing reductions
A plan with a lower monthly premium may have a higher deductible or greater out-of-pocket costs when you receive care. A plan with a higher premium may provide a different balance between monthly expenses and medical costs.
For this reason, comparing only the monthly premium can produce a misleading picture of the total cost.
What Is the Premium Tax Credit?
The Premium Tax Credit is a refundable federal tax credit that can reduce the amount eligible people pay for Marketplace health insurance premiums.
The Marketplace Health Insurance estimates eligibility using information such as household income and family circumstances. Eligible consumers can generally choose to receive some or all of the estimated credit in advance, with the payment sent to the insurance company to reduce the monthly premium.
The credit is based on your actual circumstances for the tax year, so changes in income or household circumstances can affect the final amount.
If you receive advance premium tax credits, you generally need to reconcile those payments when filing your federal tax return. Keeping your Marketplace information updated is therefore important.
What Are Cost-Sharing Reductions?
Cost-sharing reductions are another form of financial assistance available to some Marketplace applicants.
Unlike a premium tax credit, which primarily reduces the monthly premium, cost-sharing reductions can reduce expenses such as deductibles, copayments, coinsurance, and the out-of-pocket maximum.
If you qualify for cost-sharing reductions, you generally need to choose a Silver plan to receive these additional savings.
This makes it important to compare the actual coverage and out-of-pocket costs of Silver plans rather than choosing a plan solely because its monthly premium appears low.
Marketplace Metal Levels Explained
Marketplace plans are commonly grouped into metal categories. These categories help consumers compare how plans generally divide healthcare costs between the insurer and the member.
Bronze
Bronze plans generally have lower monthly premiums and higher costs when you receive covered healthcare services.
They may appeal to people who want to keep monthly premiums lower and do not expect to use many healthcare services, although individual costs vary by plan.
Silver
Silver plans sit between Bronze and Gold in the metal-level structure.
Silver plans can be particularly important for people who qualify for cost-sharing reductions because those additional savings generally apply only when a qualifying person selects a Silver plan.
Gold
Gold plans generally have higher monthly premiums than Bronze plans but may provide lower costs when covered healthcare services are used.
They can be worth comparing for people who expect to use healthcare more frequently.
Platinum
Platinum plans generally have the highest premiums among the standard metal categories but lower cost sharing for covered services.
The best category depends on your expected healthcare needs and financial situation rather than the metal name alone.
What Does Marketplace Insurance Cover?
Marketplace plans cover a set of essential health benefits required under the ACA.
These include categories such as:
• Emergency services
• Hospitalization
• Prescription drugs
• Laboratory services
• Preventive and wellness services
• Mental health and substance use disorder services
• Maternity and newborn care
• Rehabilitative and habilitative services
• Pediatric services
Specific benefits, provider networks, deductibles, copayments, and other plan terms can differ between plans.
Before enrolling, review the plan documents and provider network to make sure the coverage fits your needs.
Marketplace Health Insurance and Pre-Existing Conditions
Marketplace plans cannot deny coverage or charge someone more simply because they have a pre-existing condition.
This is an important ACA protection. However, having coverage does not mean every treatment, provider, medication, or service will be covered at the same cost.
A person with ongoing medical needs should pay particular attention to provider networks, prescription formularies, deductibles, coinsurance, and annual out-of-pocket limits.
When Can You Enroll?
Marketplace enrollment generally occurs during an annual Open Enrollment Period.
For HealthCare.gov, Open Enrollment for the following year’s coverage begins November 1. For example, HealthCare.gov states that Open Enrollment for 2027 coverage begins November 1, 2026.
Outside Open Enrollment, you may still be able to enroll if you qualify for a Special Enrollment Period.
Certain life events can trigger a Special Enrollment Period. Examples can include losing qualifying health coverage, moving, getting married, or having a baby.
Medicaid and CHIP have different enrollment rules and may be available outside the standard Marketplace Open Enrollment schedule.
What Is a Special Enrollment Period?
A Special Enrollment Period allows eligible people to enroll in or change Marketplace coverage outside the regular Open Enrollment period after certain qualifying life events.
Common examples include:
• Losing existing health coverage
• Losing Medicaid or CHIP eligibility
• Moving to a new area
• Getting married
• Having a baby
• Adopting a child
The rules and deadlines depend on the qualifying event, so it is important to apply promptly when a major coverage or household change occurs.
How to Compare Marketplace Health Insurance Plans
Choosing a plan involves more than finding the lowest premium.
Start by estimating how much healthcare you and your household may realistically use. Then Health Insurance compare the total financial structure of each plan.
Look at the following factors:
Monthly Premium
This is the amount you pay each month for the insurance policy, regardless of whether you use medical services.
Deductible
The deductible is the amount you may have to pay for covered services before the plan begins paying according to its coverage terms.
Copayments and Coinsurance
A copayment is generally a fixed amount for a covered service. Coinsurance is generally a percentage of the allowed cost that you pay after applicable requirements are met.
Out-of-Pocket Maximum
The out-of-pocket maximum limits how much you pay during a plan year for covered services subject to the plan’s rules.
Provider Network
Check whether your preferred doctors, hospitals, specialists, and other healthcare providers participate in the plan’s network.
Prescription Coverage
If you regularly take medication, check the plan’s drug coverage and formulary before enrolling.
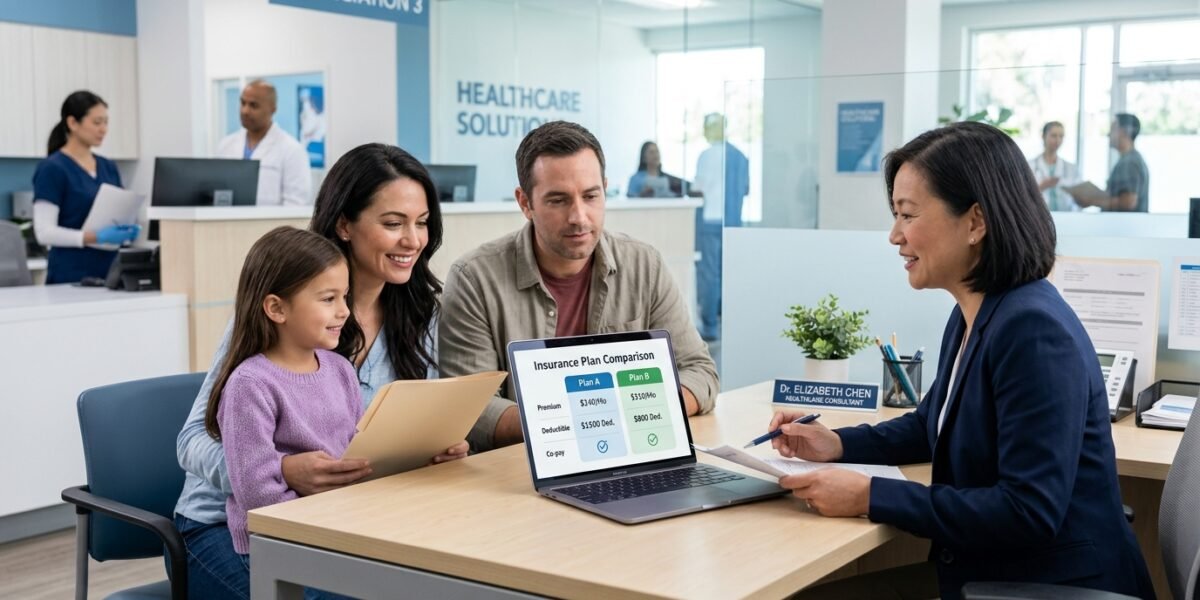
A Simple Example of Comparing Plans
Imagine two Marketplace plans are available to a household.
Plan A has a lower monthly premium but a higher deductible.
Plan B has a higher monthly premium but a lower deductible and different cost-sharing requirements.
If the household rarely uses healthcare, Plan A might appear attractive because of the lower recurring premium. If the household expects regular appointments, prescriptions, or medical treatment, Plan B could deserve closer consideration.
This does not mean one plan is universally better. The right choice depends on the household’s expected healthcare use, finances, providers, medications, and tolerance for unexpected medical expenses.
What Information Do You Need to Apply?
Having accurate information ready can make the application process easier.
Depending on your circumstances, you may need information about:
• Household members
• Estimated annual household income
• Current health coverage
• Employer-sponsored coverage
• Immigration or citizenship status
• Social Security information when applicable
• Tax filing information
• Other qualifying coverage
Income estimates are particularly important when applying for financial assistance. If your circumstances change during the year, update your Marketplace application.
Important 2026 Financial Assistance Considerations
Marketplace financial assistance can change as federal rules change.
For 2026, the enhanced premium assistance that was temporarily available in prior years ended after December 31, 2025. As a result, some consumers may see different premium assistance for 2026 than they received previously.
The actual amount of financial assistance depends on the applicant’s circumstances and applicable rules. Rather than relying on an older estimate, use the current Marketplace application and plan information for your situation.
Because tax rules and eligibility requirements can change, consumers should verify current information with HealthCare.gov and the IRS.
Common Mistakes to Avoid
One common mistake is choosing a plan based only on its monthly premium.
A low premium does not necessarily mean low overall healthcare costs.
Another mistake is failing to check the provider network. A plan may look affordable until you discover that your preferred doctor or hospital is outside the network.
People can also overlook prescription coverage. If you take regular medication, check whether your prescriptions are covered and what cost-sharing rules apply.
Another important mistake is failing to report changes. Changes in household income, family size, address, or access to other health coverage can affect Marketplace eligibility and financial assistance.
Finally, do not assume that a plan automatically renews with the same price, benefits, or financial assistance every year. Review your available options during the applicable enrollment period.
Is Marketplace Health Insurance Right for You?
Marketplace insurance may be useful if you need individual or family coverage and do not have suitable affordable coverage through an employer or another qualifying source.
It can also be valuable because the Marketplace provides a centralized way to compare plans and determine whether you qualify for financial assistance.
However, Marketplace coverage is not the only healthcare option. Depending on your circumstances, employer-sponsored insurance, Medicaid, CHIP, Medicare, or other qualifying coverage may be more appropriate.
The key is to compare your available options based on coverage, total potential costs, eligibility, and healthcare needs.
FAQ SECTION
What is marketplace health insurance?
Marketplace health insurance is health coverage purchased through an ACA Marketplace. Eligible consumers can compare plans, apply for financial assistance, and enroll in qualifying coverage.
Who can use the Health Insurance Marketplace?
Generally, people who live in the United States and meet citizenship, lawful-presence, and other eligibility requirements can use the Marketplace. People with Medicare generally cannot enroll in a Marketplace health or dental plan.
Is marketplace health insurance free?
Not necessarily. Some eligible people receive financial assistance that lowers their monthly premium or other healthcare costs, but the amount varies based on individual circumstances and the plan selected.
What is the difference between a premium and a deductible?
A premium is the amount you pay for insurance coverage, usually each month. A deductible is an amount you may have to pay for covered healthcare services before the plan begins paying according to its terms.
Can I get marketplace insurance outside Open Enrollment?
Possibly. You may qualify for a Special Enrollment Period after certain qualifying life events, such as losing qualifying coverage, moving, getting married, or having a baby. Medicaid and CHIP also have separate enrollment rules.
What is a premium tax credit?
A premium tax credit is a refundable tax credit that can reduce the amount eligible people pay for Marketplace health insurance premiums. Eligibility and the amount depend on applicable rules and household circumstances.
Are pre-existing conditions covered?
Marketplace plans cannot deny coverage or charge higher premiums simply because you have a pre-existing condition. Specific services, providers, and cost-sharing requirements still depend on the plan.
Should I choose a Bronze or Silver plan?
There is no universally best choice. Compare the monthly premium, deductible, cost sharing, provider network, expected healthcare use, and eligibility for cost-sharing reductions before selecting a plan.
Final Takeaway
Marketplace health insurance provides a structured way for eligible people in the United States to compare individual and family health plans, apply for coverage, and determine whether they qualify for financial assistance.
When comparing plans, look beyond the monthly premium. Consider deductibles, copayments, coinsurance, provider networks, prescription coverage, and the out-of-pocket maximum.
For current enrollment dates, plan availability, eligibility, and financial assistance, use the official Marketplace information for your state and verify tax-related details with the IRS. Marketplace rules and costs can change, so current information is more reliable than an older estimate.
Related Wealth Articles
Working Capital Management Tutorial Explained: A Practical Guide
Working capital management is the process of managing a business’s short-term assets and liabilities to support daily operations,…
Capital One Auto Navigator: A Guide to Car Shopping and Financing
What Is Capital One Auto Navigator? Capital One Auto Navigator is a car-shopping and financing platform designed to…
1 Discussion Comment