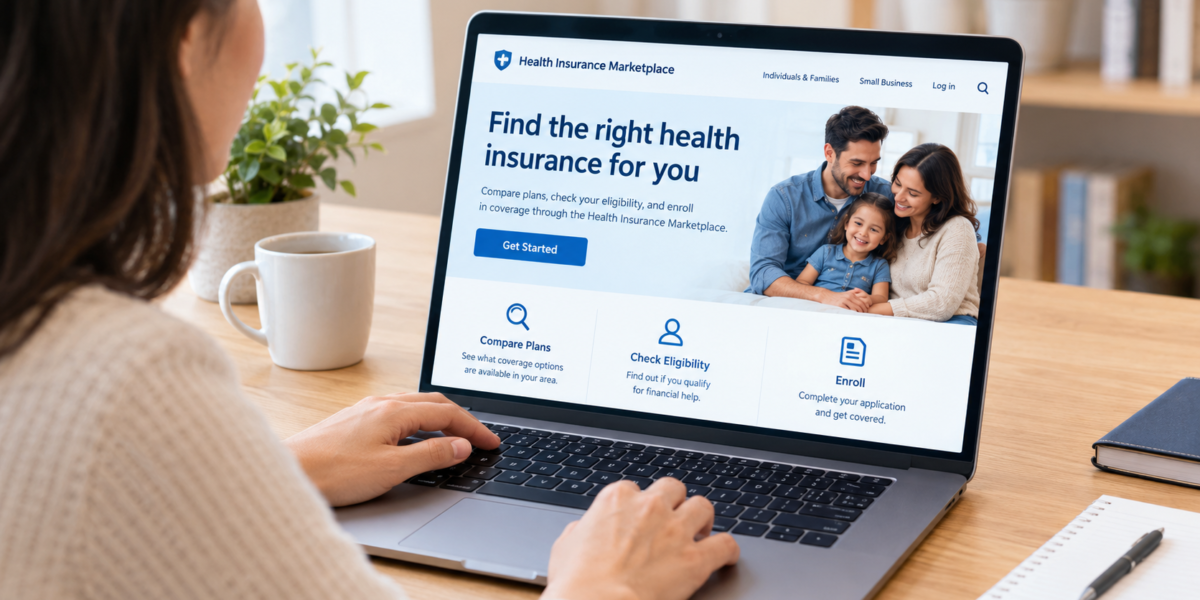
Health Insurance Marketplace: A Guide to Plans, Costs and Enrollment
What Is the Health Insurance Marketplace?
The Health Insurance Marketplace is a service that helps eligible people in the United States shop for and enroll in individual and family health insurance. The federal Marketplace is available through HealthCare.gov in most states, while some states operate their own Marketplace websites.
For many people who do not have affordable health coverage through an employer, Medicare, Medicaid, or another source, the Marketplace can provide a way to compare available health plans and determine whether they qualify for financial assistance.
The Marketplace is not a single insurance company. Instead, it is a place where eligible consumers can compare health insurance plans offered by participating insurers. The plans, prices, networks, deductibles, and other costs can vary depending on where you live and the plan you choose.
The Marketplace application can also help determine whether someone in your household may qualify for Medicaid or the Children’s Health Insurance Program, commonly called CHIP.
How Does the Health Insurance Marketplace Work?
The basic process is relatively straightforward.
You provide information about your household, location, and expected income. The Marketplace then uses that information to show available coverage options and determine whether you may qualify for savings or public programs.
You can generally:
- Create or access a Marketplace account.
- Provide household and income information.
- Review your eligibility results.
- Compare available health insurance plans.
- Review premiums, deductibles, networks, and other costs.
- Choose a plan that fits your circumstances.
- Enroll and pay the required premium to begin coverage.
HealthCare.gov says applicants should use their expected household income for the coverage year when completing an application rather than simply using the previous year’s income.
Your situation can also change after enrollment. If your income, household, or other circumstances change, updating your Marketplace application can affect your coverage options or financial assistance.
Who Can Use the Health Insurance Marketplace?
Marketplace eligibility depends on several factors.
According to HealthCare.gov, a person generally must live in the United States, be a U.S. citizen or national or a lawfully present noncitizen, and not be incarcerated to enroll through the Marketplace. People with Medicare generally cannot enroll in a Marketplace health or dental plan.
Eligibility for financial assistance is a separate question. Someone may be eligible to buy Marketplace coverage but not qualify for the same level of savings as another household.
Household income, household size, access to other qualifying coverage, and other circumstances can affect eligibility for savings.
If someone may qualify for Medicaid or CHIP, the Marketplace application can help identify that possibility and, where appropriate, securely transfer information to the relevant state agency.
When Can You Enroll?
Marketplace enrollment generally follows an annual Open Enrollment period, although certain life events can create a Special Enrollment Period.
For 2027 coverage, HealthCare.gov currently states that Open Enrollment starts November 1. HealthCare.gov also states that November 1 is the annual Open Enrollment start date and January 15 is the general end date.
Outside Open Enrollment, you may still be able to enroll if you qualify for a Special Enrollment Period. Examples can include certain situations involving losing other health coverage, moving, getting married, or having a baby.
Medicaid and CHIP have different enrollment rules. HealthCare.gov states that people can apply for Medicaid and CHIP at any time of year.
Because deadlines and eligibility circumstances can affect coverage, it is best to verify the current rules for the year you want coverage.
What Does Marketplace Health Insurance Cover?
Marketplace plans provide comprehensive health coverage, although the exact benefits, cost sharing, provider networks, and plan rules can differ.
Health insurance can involve several types of costs and coverage features, including:
- Monthly premiums
- Deductibles
- Copayments
- Coinsurance
- Out-of-pocket limits
- Prescription drug coverage
- Doctor visits
- Hospital services
- Preventive care
- Emergency services
- Specialist care
- Other covered medical services
The exact details depend on the plan.
A plan with a lower monthly premium may have higher costs when you receive medical care. Another plan may have a higher premium but lower cost sharing for certain services. Looking only at the monthly premium can therefore give an incomplete picture of the plan’s overall cost.
How Much Does Marketplace Insurance Cost?
There is no single Marketplace price for everyone.
Premiums and other costs can depend on factors such as location, household circumstances, age, plan selection, and eligibility for financial assistance.
HealthCare.gov allows consumers to preview estimated plans and prices by entering information such as ZIP code, household members, and estimated income. The final prices are determined after completing the full application and eligibility process.
When comparing plans, consider both predictable monthly expenses and possible medical costs.
For example, someone who rarely uses medical services may focus heavily on the premium and network. Someone who expects regular prescriptions, specialist visits, or other medical care may want to pay closer attention to deductibles, copayments, coinsurance, and the out-of-pocket maximum.
What Is a Premium Tax Credit?
A premium tax credit is financial assistance that can reduce the monthly premium for an eligible Marketplace plan.
The amount of assistance depends on the individual’s or household’s circumstances and eligibility. It is not automatically available to everyone who buys Marketplace insurance.
HealthCare.gov explains that Marketplace applications can determine whether applicants qualify for savings, while the final amount depends on the information provided and applicable eligibility rules.
Because income can change during the year, people receiving financial assistance should keep their Marketplace application information up to date. A significant change in income or household circumstances can affect eligibility and the amount of assistance.
What Are Cost-Sharing Reductions?
Some eligible Marketplace consumers may also qualify for additional savings on certain out-of-pocket costs.
These savings can affect expenses associated with covered medical services rather than simply reducing the monthly premium.
The important point is that two people with similar premiums may still have very different potential healthcare costs because their deductibles, copayments, coinsurance, provider networks, and other plan features differ.
Before choosing a plan, review the full cost structure rather than comparing premiums alone.
Marketplace Plans vs. Medicaid and CHIP
The Marketplace, Medicaid, and CHIP are related parts of the broader U.S. health coverage system, but they are not the same program.
Medicaid is a federal and state program that provides free or low-cost coverage to eligible people. CHIP provides coverage for eligible children and, depending on state rules, certain pregnant women. Eligibility and benefits can vary by state.
If the Marketplace application indicates that someone in the household may qualify for Medicaid or CHIP, the application process can direct the information to the appropriate state agency.
If you qualify for Medicaid that counts as qualifying health coverage, you generally cannot continue receiving premium tax credits for a Marketplace plan. HealthCare.gov advises consumers to wait for a final Medicaid or CHIP eligibility decision before ending Marketplace coverage to avoid an unintended gap.
What Should You Compare Before Choosing a Plan?
Choosing a health insurance plan should involve more than finding the lowest premium.
Consider the following factors.
Monthly Premium
The premium is the amount you pay for the insurance plan each month. A lower premium can make a plan easier to budget for, but it may come with higher cost sharing when you use healthcare services.
Deductible
The deductible is the amount you generally pay for covered services before the plan begins paying according to its applicable coverage rules.
A lower deductible may be useful for someone who expects regular healthcare expenses, although it can be associated with a higher premium.
Copayments and Coinsurance
A copayment is generally a fixed amount you pay for a covered service.
Coinsurance is generally a percentage of the allowed cost of a covered service after applicable deductible requirements have been met.
Understanding both can help you estimate what routine visits, prescriptions, specialist care, and other services could cost.
Out-of-Pocket Maximum
The out-of-pocket maximum is an important protection to review because it can limit your cost exposure for covered services under the plan, subject to the plan’s rules.
It does not necessarily mean every healthcare expense is covered once you reach the limit. Services that are not covered, premiums, and certain other expenses may be treated differently.
Provider Network
Check whether your preferred doctors, hospitals, clinics, and other healthcare providers participate in the plan’s network.
A plan that appears inexpensive may be less suitable if it does not provide convenient access to the providers you need.
Prescription Coverage
If you regularly take medication, check whether the plan covers your prescriptions and understand the applicable cost-sharing rules.
Drug formularies can differ between plans, so reviewing the plan’s prescription information before enrollment can prevent unexpected costs.
How to Choose a Marketplace Plan
A practical approach is to start with your healthcare needs rather than the plan’s advertised price.
First, estimate how often you normally visit doctors and whether you expect specialist treatment, prescriptions, or planned medical services.
Next, check the provider network. If keeping a particular doctor or hospital is important, confirm that the provider participates in the plan before enrolling.
Then compare premiums, deductibles, copayments, coinsurance, and out-of-pocket limits.
Finally, review the plan’s coverage documents and eligibility information carefully before making a decision.
HealthCare.gov provides tools for comparing available plans and estimated prices based on location and other information.
What Information Do You Need to Apply?
Having the right information available can make the application process easier.
Depending on your circumstances, you may need information about:
- Household members
- Expected household income
- Current health coverage
- Employer coverage
- Immigration or citizenship status where applicable
- Tax-related household information
- Other information requested by the application
HealthCare.gov provides an application checklist and recommends preparing relevant information before starting.
If you are estimating income, pay attention to the coverage year for which you are applying. Your expected income can be more relevant than simply copying a previous year’s figure.
What If You Lose Medicaid or CHIP?
Losing Medicaid or CHIP does not necessarily mean you must remain uninsured.
If your state determines that you are no longer eligible, you may be able to enroll in Marketplace coverage and potentially receive financial assistance if you meet the applicable requirements.
HealthCare.gov says people can apply for Marketplace coverage before their Medicaid or CHIP coverage ends in certain circumstances to help prevent a gap in coverage. The specific timing depends on the situation.
Keep documentation from your state regarding the end of Medicaid or CHIP coverage because it may be relevant when completing a Marketplace application.
Common Health Insurance Marketplace Mistakes
Choosing Only by Monthly Premium
The cheapest premium does not necessarily mean the lowest overall healthcare cost.
Compare the deductible, network, prescription coverage, copayments, coinsurance, and out-of-pocket maximum as well.
Ignoring the Provider Network
Before enrolling, check whether your preferred doctors and hospitals are included.
Using an Incorrect Income Estimate
Financial assistance can depend on income. An inaccurate estimate can affect eligibility or the amount of assistance available.
Update your Marketplace application when relevant circumstances change.
Missing Enrollment Deadlines
Open Enrollment and Special Enrollment Period rules matter. Waiting until the last moment can make the process more stressful and may limit your options.
Assuming Every Plan Works the Same Way
Marketplace plans can have significant differences in networks, costs, benefits, and plan rules. Read the plan information rather than assuming two plans are equivalent.
Ending Existing Coverage Too Early
If you are moving from Marketplace coverage to Medicaid or CHIP, do not end Marketplace coverage solely because you have been told that you may be eligible. HealthCare.gov advises waiting for a final eligibility decision to avoid a potential coverage gap.
How to Apply for Marketplace Health Insurance
You can apply through the official Marketplace website, by phone, with assistance from a trained enrollment helper, through a certified enrollment partner, or by paper application.
For most states, HealthCare.gov is the official federal Marketplace. Some states operate their own Marketplace platforms, so residents should use the appropriate Marketplace for their state.
When applying online, provide accurate household and income information and carefully review the eligibility results.
If you need assistance, HealthCare.gov also provides access to trained helpers who can assist with applications and plan comparisons.
How to Avoid Health Insurance Marketplace Scams
Health insurance involves sensitive personal and financial information, so be careful when responding to unsolicited offers.
Avoid giving personal information to anyone promising cash, gifts, unusually cheap coverage, or other incentives in exchange for your information.
HealthCare.gov specifically warns consumers to protect their personal information and provides resources for identifying and reporting potential fraud.
When possible, start with the official Marketplace website or verify that an enrollment helper or partner is authorized before providing sensitive information.
Health Insurance Marketplace: Key Takeaway
The Health Insurance Marketplace gives eligible U.S. consumers a way to compare individual and family health plans, apply for coverage, and find out whether they may qualify for financial assistance or programs such as Medicaid and CHIP.
The best plan is not necessarily the one with the lowest monthly premium. Consider the complete cost structure, provider network, prescription coverage, expected healthcare needs, and available financial assistance.
Marketplace rules and plan availability can change from year to year. For current enrollment dates, eligibility decisions, prices, and coverage details, verify information through the official Marketplace serving your state before enrolling.
FAQ
Is the Health Insurance Marketplace the same as Obamacare?
The terms are often used together, but they are not exactly the same. The Marketplace is the system through which eligible consumers can shop for and enroll in qualifying individual and family health coverage under the Affordable Care Act framework.
Who can get health insurance through the Marketplace?
Generally, people who live in the United States, meet applicable citizenship or lawful-presence requirements, and are not incarcerated can use the Marketplace. Medicare beneficiaries generally cannot enroll in a Marketplace health or dental plan.
Can I get financial help with Marketplace insurance?
You may qualify for financial assistance depending on your household circumstances, income, and other eligibility factors. The Marketplace application can determine whether you qualify for available savings.
Can I enroll in Marketplace insurance at any time?
Generally, Marketplace enrollment follows Open Enrollment unless you qualify for a Special Enrollment Period. Medicaid and CHIP applications can generally be made throughout the year.
What happens if I cannot afford a Marketplace plan?
Complete the Marketplace application rather than assuming you will have to pay the full listed price. The application can determine whether you qualify for savings or whether someone in your household may qualify for Medicaid or CHIP.
Can I change my Marketplace plan?
Changes are generally possible during Open Enrollment, while certain life events can create a Special Enrollment Period. Medicaid or CHIP eligibility can also change your available coverage options.
Can I use Marketplace insurance outside the United States?
Marketplace coverage is primarily designed for healthcare provided within the United States. If you regularly travel or live outside the country, review the plan’s rules and consider whether additional travel or international health coverage may be appropriate.
Where should I apply for Marketplace coverage?
For most states, HealthCare.gov is the official federal Marketplace. Some states operate their own Marketplace websites. Use the Marketplace serving your state rather than relying on an unfamiliar website.
You may also find blog on below
What Does Renters Insurance Cover?
Related Wealth Articles
American First Finance: A Complete Guide to Payment Options, Costs, and Customer Considerations
What Is American First Finance? American First Finance is a consumer financing company that offers payment solutions through…
Capital One Customer Service 24/7 Phone Number: How to Get Help
Finding the Capital One customer service 24/7 phone number can help you determine how to contact the company…