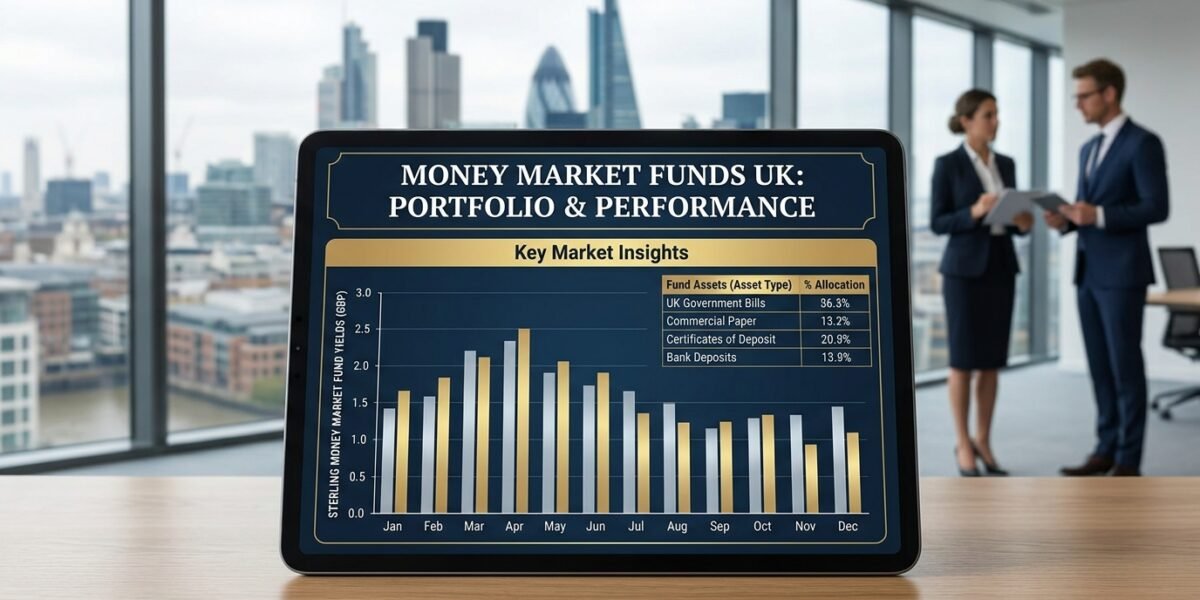
Money Market Funds UK: A Complete Guide
Money market funds UK investors can access are investment funds designed to hold high quality, short term assets such as government securities, bank deposits and other short term money market instruments. They are commonly used for cash management because they aim to provide relatively stable value and easy access to invested money while generating a return from short term interest rates.
However, a money market funds UK is not the same as a bank savings account. Your money is invested in a fund, so the value can fluctuate and the investment does not automatically receive the same protection as an eligible bank deposit. The Financial Conduct Authority states that money market funds UK invest in high quality short term assets and are not guaranteed investments.
This guide explains how money market funds work in the UK, the different types, potential benefits and risks, tax considerations, FSCS protection, and the factors investors should check before choosing one.
What Are Money Market Funds in the UK?
A money market funds Uk, often abbreviated to MMF, is a collective investment fund that pools money from investors and invests it in short term, generally high quality financial instruments.
The underlying investments can include instruments such as:
- UK government securities and other high quality short term debt
- Short term bank deposits
- Certificates of deposit
- Commercial paper
- Repurchase agreements
- Other eligible money market instruments
The objective is generally to provide liquidity, preserve capital as far as possible and generate income from short term interest rates. These objectives do not mean that capital is guaranteed.
The FCA describes MMFs as funds that pool investors’ money and make low risk investments in high quality short term assets. MMFs are regulated with requirements relating to their portfolios, liquidity and valuation.
This makes money market funds particularly relevant to investors who want an investment vehicle that is generally less exposed to long term interest rate and equity market movements than a conventional bond or equity fund.
How Do Money Market Funds UK Work?
When you invest in a money market funds UK, you purchase units or shares in the fund. The fund manager then invests the pooled money according to the fund’s investment objective and regulatory requirements.
The return generated by the underlying assets can be passed to investors through distributions or reflected in the value of the investment, depending on the fund and share class.
For example, imagine a hypothetical investor puts £10,000 into a sterling money market fund. The fund invests across eligible short term assets. If those assets generate income, the fund may distribute the income or accumulate it, depending on the share class.
This example does not represent a guaranteed return. Actual performance depends on the fund’s investments, fees, market conditions, interest rates and other factors.
One important point is that the fund manager does not simply keep investors’ money as cash. The money is invested in financial instruments that carry their own credit, liquidity, market and operational risks.
Why Do Investors Use Money Market Funds UK?
Money market funds UK give me pure and professional feature image of money market funds are often used as a cash management tool rather than as a long term growth investment.
Potential uses include holding money temporarily while deciding where to invest it, managing a cash allocation within an investment portfolio, or seeking exposure to short term interest rates through a diversified fund.
They can also be useful for investors who want access to a range of short term instruments without purchasing each security individually.
The FCA notes that MMFs are widely used by financial institutions, insurers, pension funds, investment funds and larger companies, although retail investors can also encounter them through investment platforms and fund providers.
Types of Money Market Funds in the UK
Understanding the type of money market funds uk is important because different structures can have different valuation and liquidity characteristics.
Under the UK regulatory framework, the main MMF categories include variable net asset value funds, low volatility net asset value funds and public debt constant net asset value funds. The FCA’s proposed framework has retained these broad categories.
Variable NAV Money Market Funds
A variable NAV, or VNAV, fund values its units based on the net asset value of the underlying portfolio.
The unit price can therefore move up or down, even though the fund invests in short term assets.
This means investors should not think of a VNAV money market fund as being identical to cash in a bank account.
Low Volatility NAV Funds
Low volatility NAV, commonly called LVNAV, funds are designed to provide relatively stable dealing prices under specific regulatory conditions.
They still have an underlying net asset value and are subject to rules governing valuation and the relationship between the dealing price and the calculated NAV.
The important point for investors is that low volatility does not mean no volatility. The investment remains a fund rather than a guaranteed deposit.
Public Debt CNAV Funds
Public debt constant NAV funds are designed around maintaining a constant net asset value under specific regulatory conditions and investing primarily in eligible public debt and related assets.
The structure is subject to detailed regulatory requirements.
Investors should therefore look at the actual fund documentation rather than assuming that a constant or stable dealing price means the investment has the same risk characteristics as a bank deposit.
Money Market Funds vs Savings Accounts
One of the most important distinctions is between a money market funds UK and a savings account.
A savings account is a bank deposit. A money market funds UK is an investment.
| Feature | Money Market Fund | Savings Account |
|---|---|---|
| Structure | Investment fund | Bank deposit |
| Main purpose | Cash management and short term investment | Saving and holding deposits |
| Underlying exposure | Short term financial instruments | Deposit with a bank |
| Capital guarantee | No automatic guarantee | Deposit protection may apply if eligible |
| Value | Can vary depending on fund structure | Deposit balance does not normally fluctuate with market prices |
| Return | Depends on underlying investments and fees | Usually stated as interest rate |
| Regulation | Investment fund rules | Banking and deposit rules |
| Access | Depends on fund/platform dealing arrangements | Depends on account terms |
The distinction in protection is especially important. FSCS states that eligible investment claims can be protected up to £85,000 per eligible person per firm in certain circumstances, but FSCS does not compensate investors simply because an investment performed poorly.
By contrast, the FSCS deposit protection limit for eligible deposits at banks, building societies and credit unions is currently £120,000 per eligible person per eligible firm.
Therefore, investors should never assume that putting money into a money market fund gives them the same protection as putting money into a protected bank deposit.
Are Money Market Funds Safe in the UK?
Money market funds UK are generally designed around relatively short term and high quality assets, but they are not risk free.
The FCA explicitly states that investments in MMFs are not guaranteed, although investors will usually receive all or almost all of their investment back.
Potential risks include:
Credit Risk
The institutions and issuers behind the fund’s investments may experience financial problems.
A fund normally reduces concentration risk by holding a portfolio rather than relying on a single issuer, but diversification does not eliminate credit risk.
Liquidity Risk
The fund may need to sell assets to meet investor redemptions.
During severe market stress, assets that normally appear highly liquid can become more difficult or expensive to sell.
This is one reason UK regulators have been reviewing the resilience of the money market fund sector.
Interest Rate Risk
Money market funds UK invest heavily in short term instruments, so their income can be affected by changes in short term interest rates.
When central bank rates fall, the income available from newly purchased short term instruments can also fall over time.
When rates rise, money market funds may benefit from higher yields on newly invested money, although the effect depends on the fund’s portfolio and timing.
NAV Risk
Some money market funds UK use variable NAV structures, meaning their unit price can move.
Even funds designed to maintain a relatively stable dealing price can be subject to specific regulatory conditions and risks.
Operational and Counterparty Risk
A fund can also face risks associated with counterparties, settlement systems, custodians, fund administrators and other financial infrastructure.
These risks are part of investing and are one reason investors should understand the fund provider and documentation before investing.
Are Money Market Funds UK Covered by FSCS?
This is an area where investors need to be particularly careful.
FSCS protection is not simply a blanket guarantee on every investment held through a UK investment platform.
The FSCS explains that investment protection can apply where an authorised firm fails and there is a valid eligible claim, with compensation of up to £85,000 per eligible person per firm for failures after 1 April 2019. However, FSCS does not cover losses caused simply by poor investment performance.
That distinction matters.
If a money market funds UK falls in value because the underlying investments perform poorly, that does not automatically create an FSCS compensation claim.
Investors should check:
- Whether the platform or provider is authorised.
- What activity the firm is performing.
- Whether the particular investment arrangement is eligible for FSCS protection.
- What happens to client assets if the provider fails.
- Whether the risk being considered is provider failure or investment loss.
Do not treat FSCS protection as equivalent to the guarantee on an eligible bank deposit.
What Returns Can Money Market Funds UK Investors Expect?
There is no single fixed return for all money market funds UK.
Returns depend on the underlying portfolio, prevailing short term interest rates, fund expenses, dealing arrangements, currency and other factors.
Short term interest rates are particularly important because MMFs generally invest in short duration assets.
For context, Bank of England data published in September 2026 showed that the average effective rate on outstanding individual sight deposits at UK monetary financial institutions was 1.65%, while the effective rate on outstanding time deposits was 3.39% in July 2026. These are banking sector averages, not money market fund returns, and should not be used as a forecast for an MMF.
This illustrates why comparing a money market fund with a savings account requires more than looking at one headline percentage.
An investor should compare the fund’s current yield or distribution information with relevant savings alternatives while considering fees, access, tax and risk.
Do Money Market Funds Pay Interest?
Technically, investors should be careful with the word interest.
A money market funds UK earns income from the assets it holds. Depending on the fund structure and share class, that income may be distributed to investors or retained within the fund.
The investor may therefore see a distribution, an increase in the value of accumulation units, or another form of return depending on the product.
The tax treatment can also depend on the nature of the distribution and the investor’s circumstances.
This is different from a bank savings account, where the bank normally pays interest on the deposit according to the account’s terms.
Tax on Money Market Funds in the UK
Tax treatment is an important part of comparing money market funds UK with savings accounts.
The tax position depends on factors such as the type of fund, the nature of distributions, whether the investment is held within an ISA or pension wrapper, and the investor’s individual tax circumstances.
HMRC’s investment fund guidance explains that investors in authorised investment funds can be subject to income tax or corporation tax depending on their circumstances. HMRC also distinguishes between dividend distributions and interest distributions.
This means investors should not assume that every return from a money market fund is taxed in exactly the same way as bank interest.
For a UK investor, it can therefore be useful to check:
- Whether the fund is an authorised investment fund.
- Whether it makes interest or dividend distributions.
- Whether the fund is held inside an ISA or pension.
- Whether the investment generates taxable income or gains.
- Whether the investor is subject to income tax or corporation tax.
- Whether the fund has a reporting or distributing status where relevant.
Tax rules can change, so current HMRC guidance should be checked before making a decision.
Money Market Funds and ISAs
Some money market funds UK may be available through investment platforms that also offer Stocks and Shares ISAs, but availability and ISA eligibility depend on the specific fund and platform.
Holding an eligible investment within an ISA can change the tax treatment compared with holding the same investment outside a tax wrapper.
Investors should therefore check both the fund’s eligibility and the ISA provider’s available investments rather than assuming that every money market fund can automatically be placed inside an ISA.
What Are the Benefits of Money Market Funds UK?
Money market funds UK can have several potential advantages.
First, they provide access to a diversified portfolio of short term instruments through one investment.
Second, they can offer a way of managing cash within an investment portfolio without moving entirely into longer duration bonds or equities.
Third, professional fund management means investors do not normally need to select individual certificates of deposit, commercial paper or other short term instruments themselves.
Fourth, many MMFs are designed around liquidity, making them potentially useful for investors who may need access to their money relatively soon.
However, these advantages should always be considered alongside the investment risks and costs.
What Are the Disadvantages?
The main disadvantage is that a money market funds UK is still an investment.
There is no universal guarantee that your capital will remain unchanged.
Other disadvantages can include fund charges, dealing restrictions, settlement times, tax complexity and potentially lower returns when short term interest rates decline.
A fund may also have different risks from a bank account even when its objective appears similar to cash management.
The right comparison therefore depends on why you are holding the money.
How to Choose a Money Market Funds in the UK
If you are comparing money market funds UK, do not choose solely on the basis of the highest advertised yield.
Consider the following factors.
1. Fund Type
Determine whether the fund is VNAV, LVNAV or public debt CNAV, where applicable.
Understand how the fund calculates its NAV and how subscriptions and redemptions work.
2. Currency
For a UK investor, a sterling money market fund may avoid the direct currency exposure that comes with investing in a fund denominated in another currency.
However, the currency of the fund and the currency of the underlying assets are separate considerations.
3. Underlying Investments
Read the fund documentation to understand what the fund actually holds.
Look for information about issuer concentration, government exposure, bank exposure, maturity and credit quality.
4. Yield and Fees
Compare the return after considering the fund’s ongoing charges and other applicable costs.
A fund showing a higher headline yield is not automatically better if its costs, risk profile or liquidity arrangements are less suitable for your purpose.
5. Liquidity and Dealing
Check when you can buy and sell units, when redemptions are processed and when money becomes available in your account.
Do not assume that an investment fund provides instant access simply because it invests in short term assets.
6. Fund Manager and Provider
Check the regulatory status of the fund manager and platform.
Look at the fund’s official documentation rather than relying entirely on comparison websites or promotional material.
7. Tax Treatment
Understand whether the fund generates interest distributions, dividend distributions or other taxable returns and how that interacts with your own tax position.
Money Market Funds vs Short Term Bond Funds
These two types of funds can appear similar because both may invest in fixed income securities.
However, their objectives and risk profiles can differ significantly.
Money market funds generally focus on very short term instruments and liquidity.
Short term bond funds may hold bonds with longer maturities and therefore can experience greater price movements when interest rates or credit conditions change.
An investor looking for a cash management vehicle should therefore not automatically replace a money market fund with a short duration bond fund simply because the two products both invest in debt securities.
The investment objective and duration of the portfolio matter.
Money Market Funds vs Cash Funds
The term cash fund can be used differently by different providers.
Some products marketed as cash funds may be money market funds, while others may use different structures.
Always read the fund’s formal classification, objective and investment policy instead of relying on the product name alone.
The name cash or money market does not remove the need to understand the underlying investments and risks.
Money Market Funds UK Regulation in 2026
The UK regulatory framework for MMFs is undergoing reform.
In May 2026, HM Treasury and the FCA announced plans to reform the Money Market funds UK Regulations. The government said the reforms are intended to strengthen the resilience of MMFs while allowing them to continue serving their cash management role.
In June 2026, the FCA published an update on its proposed approach. It said the government expected legislation to replace the existing Money Market funds UK Regulation by the end of 2026, subject to the relevant legislative and regulatory processes. The FCA also said it intended to introduce stronger liquidity expectations and other measures, including changes relating to stable NAV funds and investor concentration.
The FCA’s June proposal included a supervisory expectation that stable NAV MMFs would need 40% weekly liquid assets and variable NAV MMFs 20% to meet the proposed resilience requirement, while retaining current minimum weekly liquid asset requirements in rules. These were proposals subject to final consideration and sign off, rather than figures that should be treated as permanent final requirements.
For investors, the practical lesson is simple: Money Market Funds UK regulation is evolving. Anyone making an investment decision should check the latest FCA, HM Treasury and fund provider information rather than relying on an old article.
Common Mistakes Investors Make
Treating an Money Market funds UK Like a Bank Account
A money market funds UK can look similar to a savings product because it focuses on short term assets, but it is an investment fund.
The risks and protection arrangements are different.
Choosing Only by Yield
The highest displayed yield is not necessarily the most suitable option.
Check the fund’s costs, underlying assets, liquidity, tax treatment and risk characteristics.
Ignoring Fund Charges
Even relatively small ongoing charges can affect the amount an investor receives.
Compare net returns where reliable information is available.
Assuming Stable NAV Means Guaranteed Capital
A stable or low volatility NAV structure is not the same thing as a government or bank guarantee.
Understand the fund’s specific structure and regulatory conditions.
Forgetting About Tax
A headline return before tax may not equal the amount you ultimately keep.
Tax treatment should be considered alongside the fund’s investment characteristics.
Ignoring Access Times
If money is needed for an emergency or a payment with a fixed deadline, check dealing and settlement arrangements before investing.
Short term investments are not necessarily instant access accounts.
A Simple Hypothetical Example
Suppose an investor has £20,000 that they expect to use within several months.
They could compare a savings account with an eligible money market fund.
The savings account may provide a stated interest rate and deposit protection subject to the FSCS rules.
The money market funds UK may invest in short term instruments and generate a return based on the portfolio’s income. However, the investment is subject to fund related risks, charges and potentially different tax treatment.
The investor should therefore compare the net expected return, accessibility, protection, tax treatment and risk rather than simply choosing the product with the highest advertised percentage.
This is a hypothetical illustration, not a prediction of actual returns.
Questions to Ask Before Investing
Before investing in a Money Market funds UK, consider asking:
- What type of Money Market funds is this?
- What assets does the fund hold?
- What is the fund’s current yield and how is it calculated?
- What fees apply?
- How quickly can I redeem my investment?
- Can the value of my investment fall?
- What type of FSCS protection, if any, applies?
- How is the fund taxed?
- Is it eligible for the account or tax wrapper I intend to use?
- Who manages the fund?
- Is the fund and provider authorised for the relevant activity?
- What happens during periods of severe market stress?
These questions can help distinguish a genuinely suitable cash management product from one that merely appears attractive because of its headline return.
Frequently Asked Questions
Are money market funds safe in the UK?
Money market funds UK are designed to invest in high quality short term assets and are subject to regulatory requirements, but they are not risk free or guaranteed. The value can be affected by credit, liquidity, market and operational risks.
Do money market funds UK have FSCS protection?
FSCS investment protection may apply in certain circumstances when an authorised firm fails, but it does not protect investors against ordinary investment losses or poor performance. The investment protection limit is generally up to £85,000 per eligible person per firm for relevant claims.
Are money market funds UK better than savings accounts?
They are different products rather than direct substitutes. A savings account is a bank deposit, while a money market funds UK is an investment. The appropriate choice depends on factors such as access, risk, tax treatment, return and protection.
Can money market funds UK lose money?
Yes. Money market funds UK are not guaranteed investments. Some structures are designed to maintain a stable or low volatility NAV, but this does not eliminate investment risk.
Do money market funds pay interest?
They earn income from the assets in their portfolios. Depending on the fund and share class, that income may be distributed to investors or retained within the fund. The tax treatment depends on the fund and investor circumstances.
Are money market funds tax free in the UK?
Not generally. Tax treatment depends on the fund structure, type of distribution, tax wrapper and investor circumstances. HMRC provides specific guidance on the taxation of authorised investment funds and their investors.
Can I hold a money market fund in an ISA?
Some money market funds UK may be available through investment platforms offering Stocks and Shares ISAs, but eligibility depends on the specific fund and platform. Check the provider’s current list of eligible investments.
Will Money Market Funds UK rules change?
The UK government and FCA announced plans in 2026 to replace the existing MMF regulatory framework and strengthen resilience. The FCA said legislation was expected to be introduced by the end of 2026, with new FCA rules planned alongside it. Investors should check the latest regulatory position because the reforms were still progressing.
Authoritative Sources to Check
For current information, readers should verify details with authoritative sources rather than relying on static articles.
The Financial Conduct Authority is the key source for UK financial regulation and MMF regulatory developments. Its June 2026 update explains the proposed changes to the UK MMF framework.
HM Treasury published the government’s May 2026 announcement concerning reforms to the Money Market Funds UK Regulations.
The Financial Services Compensation Scheme provides information about investment and deposit protection and explains the circumstances in which compensation may apply.
HM Revenue & Customs provides guidance on the taxation of authorised investment funds and investors.
The Bank of England publishes UK interest rate and banking sector statistics that can provide useful context when assessing short term interest rate conditions.
Final Thoughts
Money market funds UK investors can access provide a way to invest in diversified portfolios of short term financial instruments while maintaining a strong focus on liquidity and relatively stable value.
They can be useful for cash management, but they should not automatically be treated as equivalent to savings accounts or cash deposits. The underlying assets, fund structure, fees, liquidity arrangements, tax treatment and protection framework all matter.
The most important distinction is that a money market fund is an investment. Even when the fund invests in high quality short term assets and is designed to keep its value relatively stable, there is no universal guarantee against losses.
UK investors should also pay attention to the regulatory changes taking place during 2026. HM Treasury and the FCA are working on reforms intended to strengthen the resilience of money market funds, so the latest official information should be checked before relying on older descriptions of the rules.
For anyone comparing a money market funds UK with a savings account, the most useful approach is to look beyond the headline return. Compare risk, access, fees, tax, underlying investments and applicable protection together. That gives a much clearer picture of what the product is actually designed to do and whether it fits the investor’s particular circumstances.
Related Wealth Articles
American First Finance: A Complete Guide to Payment Options, Costs, and Customer Considerations
What Is American First Finance? American First Finance is a consumer financing company that offers payment solutions through…
Capital One Customer Service 24/7 Phone Number: How to Get Help
Finding the Capital One customer service 24/7 phone number can help you determine how to contact the company…
1 Discussion Comment